The real risk is not that your company uses spreadsheets. It is that a file, dashboard, document, or individual employee may have quietly become the place where critical business decisions are actually made.
Ask a leadership team where an important business decision comes from and the answer may sound reassuring: Finance owns it. Operations reviews it. The department head approves it.
Then watch what actually happens.
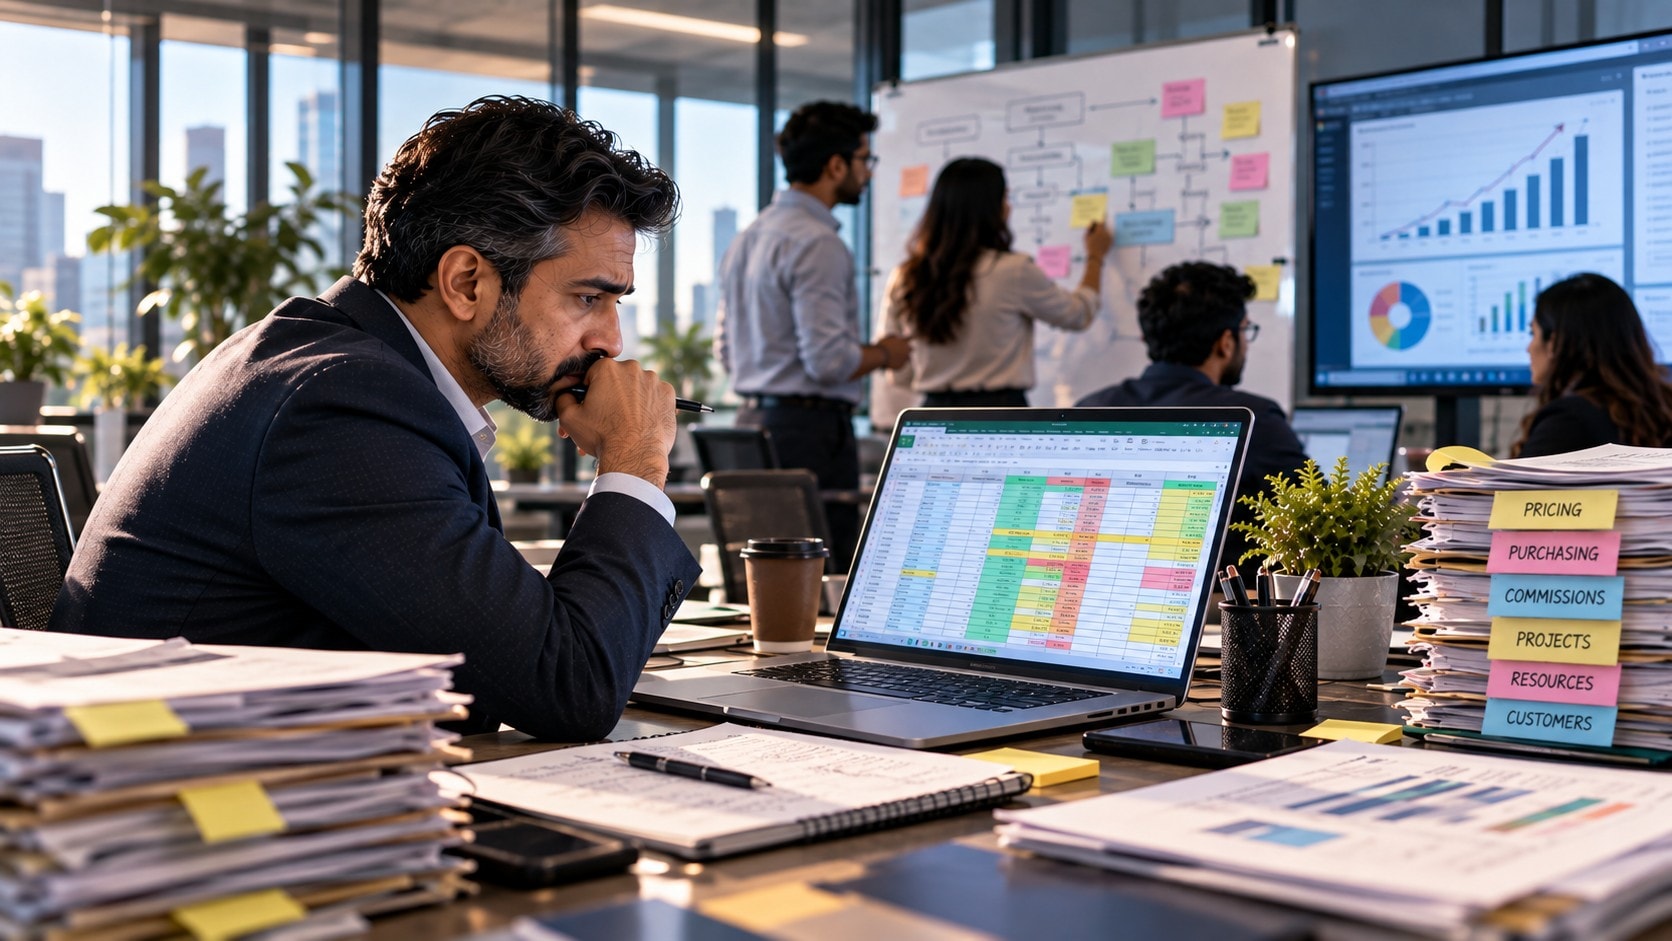
Someone opens a spreadsheet. A formula calculates the margin. A hidden tab contains the latest pricing assumptions. One employee knows which cells need to be adjusted. Another person checks a separate document before confirming whether the company can make the commitment.
The official organization chart says one thing. The real spreadsheet dependency says something else.
Spreadsheets are useful tools. The problem begins when a file stops supporting a decision and quietly becomes the decision system itself. Pricing, commissions, purchasing, project profitability, resource allocation, delivery capacity, or customer commitments may depend on logic that is poorly documented, difficult to audit, and understood by only one or two people.
That creates an operational risk that is easy to miss because nothing appears broken. The file opens. The formulas calculate. The experienced employee knows what to do.
Until the business grows, the assumptions change, the owner of the file is unavailable, or leadership discovers that a critical decision has been running on rules nobody formally agreed to.
Why Is One Spreadsheet Quietly Running the Company?
A spreadsheet starts running the company when important decisions depend on formulas, assumptions, manual updates, or knowledge inside the file that are not represented in the formal operating process. The risk increases when few people understand the logic, changes are difficult to trace, or other teams cannot make the same decision without consulting the file's owner.
This usually happens gradually.
A spreadsheet is created to solve a practical problem.
Finance needs a faster way to calculate project margins.
Sales needs a pricing model.
Operations needs to decide where limited resources should be assigned.
Purchasing needs a way to determine reorder quantities.
Management needs a simple dashboard before the formal systems can provide one.
None of this is inherently wrong.
The spreadsheet is often useful precisely because it is flexible. A capable employee can build something quickly without waiting for software development, system configuration, or a larger process redesign.
The problem appears later.
A temporary tool becomes permanent infrastructure
The company keeps growing, but the decision mechanism does not.
More people begin relying on the file.
Additional tabs are added.
New formulas appear.
Special cases are handled manually.
Another employee creates a copy because they need a slightly different view.
Eventually, nobody thinks of the spreadsheet as temporary.
It has become part of how the company operates.
The file often contains more than data
Leadership may describe the workbook as a report or tracker.
Look more closely and it may contain business rules.
For example:
- which margin makes a project acceptable;
- how salesperson commissions are calculated;
- when a purchase should be approved;
- how available staff are allocated between projects;
- which customers receive special pricing;
- how delivery dates are estimated;
- which costs are included in profitability calculations.
Those are not merely spreadsheet operations.
They are business decisions expressed through cells and formulas.
The real owner may be whoever understands the formulas
Officially, a department leader may own the decision.
Operationally, the person who understands the spreadsheet may hold more control than the organization realizes.
When somebody asks, “Can we offer this price?” the manager may wait for that employee to update the model.
When leadership asks whether a project is profitable, one person may know which costs must be manually corrected before the number can be trusted.
When resource capacity changes, someone may need to adjust several assumptions that are not documented anywhere else.
That creates key-person dependency around decisions that should belong to the business.
The dependency can remain invisible while everything works
Hidden decision systems rarely attract attention when the experienced people are available and the business environment is familiar.
The weakness appears when something changes.
- The file owner takes leave or leaves the company.
- A new manager questions how the result was calculated.
- The business introduces a new product or pricing model.
- Two versions of the spreadsheet produce different answers.
- A formula is changed without a clear review process.
- Leadership needs to explain why a decision was made months earlier.
- Transaction volume grows beyond what manual updates can reliably support.
At that point, the company discovers that the spreadsheet was not simply helping the operation.
It was holding part of the operating model together.
The Risk Is Not Excel. It Is Invisible Decision Logic.
Spreadsheets are not automatically a business problem. They become risky when critical decision logic is hidden inside formulas, manual adjustments, private knowledge, or uncontrolled versions. The core issue is whether the organization can explain who owns the decision, which rules apply, where the data comes from, and how another qualified person could reproduce the result.
Replacing every spreadsheet with software would be the wrong response.
Many spreadsheets are exactly where they should be.
They are excellent for:
- exploratory analysis;
- financial modelling;
- scenario planning;
- temporary calculations;
- one-off data reviews;
- early-stage experimentation.
The concern is not the format.
It is operational dependency.
Ask whether the spreadsheet supports the decision or defines it
There is an important difference between analysis and operational control.
A finance leader may use a spreadsheet to explore several pricing scenarios before making a judgment. That is analysis.
But if every salesperson must ask one employee to run a workbook before knowing what price can be offered, the file has become part of the operating process.
The same distinction applies elsewhere.
A capacity model used during quarterly planning can be useful analysis.
A private workbook that determines every week's project assignments may be an operational dependency.
Hidden assumptions are often more dangerous than visible formulas
A formula can be inspected.
The reasoning behind it may be much harder to recover.
Why is this margin threshold used?
Why is one customer category treated differently?
Why does this cost get excluded?
Why does the model use capacity from last month rather than current availability?
Why is one employee manually overriding the calculated result?
If those answers exist only in someone's memory, the organization does not fully own its decision logic.
Version problems can become decision problems
Duplicate spreadsheets create more than administrative confusion.
They can create competing versions of business policy.
Sales may calculate margin using one workbook.
Finance may use an updated cost assumption.
Operations may maintain another file because it needs a different resource view.
Each team believes its numbers are reasonable.
Leadership then spends time reconciling not only data, but the rules behind the data.
For companies whose problem has progressed into broad cross-file data fragmentation, KSoft Technologies also maintains a practical guide on when businesses outgrow spreadsheet-based operations.
Visibility without accountability is still fragile
Moving the spreadsheet into a shared drive does not solve the underlying issue.
Neither does placing the numbers on a dashboard.
Leadership still needs clear answers to five questions:
- Who owns the business decision?
- Which inputs are authoritative?
- Which rules determine the normal outcome?
- Who can approve an exception?
- How is the decision reviewed when assumptions change?
A reliable operating system makes those answers explicit.
A fragile one leaves them buried in a file, a dashboard, a document, or one person's working knowledge.
The warning sign is not that the company uses spreadsheets. It is that the business cannot make an important decision confidently without a particular spreadsheet—or the particular person who knows how to interpret it.
Which Critical Decisions Depend on a File Only One Person Understands?
Identify where pricing, profitability, resource, purchasing, or customer commitments rely on hidden rules instead of clear operational ownership.
Assess Your Decision-System GapsWhich Business Decisions Should Never Depend on One File or Person?
Decisions with material financial, customer, resource, compliance, or delivery impact should not depend on a single uncontrolled file or one person's undocumented knowledge. Spreadsheets can still support analysis, but critical decisions need defined ownership, trusted inputs, explicit rules, controlled exceptions, and enough visibility for another qualified person to understand and reproduce the process.
The higher the consequence of a decision, the stronger the operating controls around it should be.
Leadership does not need enterprise software for every calculation.
It does need confidence that important decisions belong to the organization rather than to the tool used to calculate them.
Pricing decisions
Pricing frequently begins in a spreadsheet because the business needs flexibility.
That can work well.
Risk increases when the workbook becomes the only place that defines:
- minimum acceptable margin;
- discount limits;
- customer-specific pricing;
- product or service cost assumptions;
- who can approve an exception.
Leadership should be able to state the pricing policy independently of the spreadsheet.
The file may calculate the answer, but it should not be the only place where the rule exists.
Project profitability
Project-based businesses often maintain margin models outside their accounting or delivery systems.
The model may include labor cost, subcontractors, expenses, utilization, overhead assumptions, and expected billing.
The operational risk appears when different managers calculate profitability differently or when one person knows which costs should be included.
Leadership then has to ask a more basic question:
Are we looking at a calculation, or are we looking at a company policy about how profitability is defined?
If profitability affects project acceptance, bonuses, staffing, or customer negotiations, the definition needs explicit ownership.
Sales commissions and incentives
Compensation calculations require particular clarity because they directly affect employees.
A spreadsheet may be perfectly appropriate for calculating commissions.
But the company should not depend on undocumented logic such as:
- manual exclusions;
- inconsistent treatment of credits or refunds;
- old commission rates retained for certain employees;
- formulas that only one administrator understands;
- changes that are not tied to an approved compensation rule.
The compensation policy should exist independently of the calculation file.
Resource allocation
Resource planning spreadsheets are common in service, technology, consulting, and project-based companies.
They can be useful for visualizing availability.
The concern is when a workbook quietly becomes the place where strategic trade-offs are made without clear ownership.
Which customer gets the most experienced team?
Which project is delayed?
Which internal initiative loses capacity?
Which employee is considered available?
These are business decisions.
A spreadsheet may inform them, but leadership should define who owns the trade-off and what priorities guide it.
Purchasing and inventory decisions
Purchasing decisions often depend on forecasts, stock levels, supplier lead times, minimum quantities, cash availability, and expected demand.
A private workbook that combines all of these may become an unofficial purchasing engine.
The business becomes vulnerable when:
- reorder logic is understood by one buyer;
- forecast assumptions are changed manually;
- inventory values come from delayed exports;
- exceptions are handled differently each time;
- purchasing authority is unclear.
The objective is not necessarily to eliminate the planning model.
It is to make the decision rules and accountability visible outside it.
Customer commitments
Some of the most consequential hidden systems determine what the company promises customers.
A salesperson asks whether a delivery date is possible.
Someone checks capacity in a spreadsheet.
Another person verifies inventory.
A manager considers current project priorities.
The customer then receives a commitment.
If the process relies on informal interpretation, the company can make promises based on assumptions that other departments cannot see.
Customer-facing commitments need clear inputs, ownership, and escalation rules because the operational consequences extend beyond the person making the promise.
Cash and financial planning
Financial models will often remain spreadsheet-based because scenario planning requires flexibility.
That is different from allowing critical cash decisions to depend on undocumented calculations.
Leadership should understand:
- where actual financial data comes from;
- which values are assumptions;
- who can modify those assumptions;
- how scenarios differ from actual results;
- which decisions require additional review.
A flexible model can remain useful without becoming an uncontrolled financial authority.
Exception-heavy operational decisions
Hidden systems often grow around exceptions.
The standard system handles the normal case.
Everything unusual moves into a spreadsheet, email thread, shared document, or experienced employee's memory.
Over time, the “exception” process may handle a meaningful portion of the business.
That is a signal that leadership should review whether:
- the standard policy is too narrow;
- recurring exceptions should become formal rules;
- approval authority is unclear;
- a workflow needs redesign;
- the system no longer reflects how the business actually operates.
Use consequence to determine the required control
Not every spreadsheet needs the same level of governance.
A useful decision rule is to examine what happens if the result is wrong.
If an error would create only minor inconvenience, a lightweight process may be enough.
If an error could affect:
- significant revenue;
- customer commitments;
- employee compensation;
- profitability;
- cash;
- critical resources;
- contractual obligations;
- regulatory or compliance responsibilities;
then leadership should expect stronger ownership, traceability, review, and continuity.
A critical decision should survive the absence test
Imagine the person who normally owns the spreadsheet is unavailable for several weeks.
Can the company still make the decision confidently?
Can another qualified leader understand:
- the source information;
- the business rule;
- the calculation;
- the decision authority;
- the valid exceptions;
- the evidence behind the final outcome?
If the answer is no, the organization does not yet fully own the decision system.
Critical business logic can live in a spreadsheet temporarily. Critical business accountability cannot.
From Spreadsheet Logic to Owned Process: A Decision-System Framework
Moving a critical decision out of spreadsheet dependency does not mean replacing every workbook with software. It means separating the useful analysis from the operating logic, identifying who owns the decision, defining trusted inputs and normal rules, controlling exceptions, and making the process visible enough that the business can reproduce it without relying on one file or person.
The wrong sequence is:
“This spreadsheet is risky, so we need to build an application.”
A stronger sequence is:
Identify the decision, understand the current logic, separate analysis from policy, clarify ownership, standardize the repeatable rules, define exceptions, and only then decide what technology should support.
That distinction matters because the real problem may not be the spreadsheet at all.
It may be that the company has never formally designed the decision process hidden inside it.
| Decision-System Element | Leadership Question | Desired State |
|---|---|---|
| Decision | What business decision is actually being made? | One clearly defined outcome |
| Owner | Who is accountable for the decision? | One explicit business owner |
| Inputs | Which information should the decision use? | Trusted, traceable data sources |
| Rules | Which normal rules determine the result? | Visible, agreed decision logic |
| Judgment | Which parts genuinely require human interpretation? | Deliberate human decision points |
| Exceptions | When can the standard rule be overridden? | Defined authority and escalation |
| Evidence | Can the company explain how the decision was reached? | Reproducible and reviewable history |
| Technology | What should software calculate, validate, route, or record? | Technology supporting the process rather than defining it |
1. Name the decision before discussing the spreadsheet
Teams often begin with the tool.
“We need to replace the pricing spreadsheet.”
“We need a better profitability dashboard.”
“We need to automate the capacity workbook.”
These statements describe the current mechanism, not the business problem.
Start by defining the decision.
For example:
- determine whether a proposed customer price meets acceptable commercial conditions;
- determine whether a project is meeting the company's profitability definition;
- decide which work receives limited delivery capacity;
- calculate an employee's commission under an approved compensation policy;
- determine whether current inventory and supplier lead times justify a purchase.
Once the decision is clear, leadership can examine whether the spreadsheet is performing analysis, applying policy, recording the outcome, or all three.
2. Map the current decision path exactly as it happens
Do not map only the official procedure.
Follow a real decision from beginning to end.
Suppose the company is preparing a customer quote.
The documented process may say:
- Sales enters the opportunity.
- Pricing is calculated.
- A manager approves the quote.
- The customer receives it.
The actual process may be very different.
A salesperson exports customer data.
Someone copies it into a pricing workbook.
Current delivery costs are requested from Operations.
An employee adjusts one formula for a special customer category.
A manager checks whether the margin “looks reasonable.”
The final price is then entered back into the CRM.
The real operating system exists in that sequence.
Mapping it exposes dependencies the formal workflow may never show.
3. Separate data from assumptions
Critical spreadsheets commonly mix facts and assumptions in the same model.
Actual labor rates sit beside estimated utilization.
Current inventory sits beside projected demand.
Contracted prices sit beside manually estimated future costs.
That combination is normal in analysis.
The risk is treating every value as though it carries the same certainty.
Leadership should identify:
- verified source data;
- manually entered values;
- management assumptions;
- forecast values;
- judgment-based adjustments.
A decision becomes easier to review when everyone can see which parts are factual inputs and which parts are assumptions.
4. Extract the business rules from the formulas
A formula is an implementation of a rule.
Leadership needs to understand the rule itself.
Suppose a workbook calculates that a proposal needs executive approval below a particular margin.
The important business questions are:
- Who decided that threshold?
- Does it apply to every customer?
- When was it last reviewed?
- Who can approve an exception?
- Is the same rule used by every team?
If those answers are unclear, documenting the formula alone is not enough.
The organization must convert embedded logic into an explicit business rule.
5. Identify where human judgment is genuinely valuable
Not every decision should become a rigid rule.
A customer relationship may justify an unusual commercial decision.
A strategic project may receive resources that a standard allocation formula would not assign.
A supplier risk may require judgment beyond historical purchase data.
These situations do not prove the process is broken.
They prove that some decisions contain judgment.
The operating system should make the distinction clear:
- which cases follow standard rules;
- which conditions trigger human review;
- who has authority to make that judgment;
- how the exception is recorded.
This preserves flexibility without allowing every decision to become an undocumented exception.
6. Assign one owner to the business outcome
A spreadsheet may have an owner.
That is not necessarily the same as owning the decision.
The analyst maintaining a pricing workbook should not automatically become accountable for pricing strategy.
The administrator calculating commissions should not automatically become accountable for compensation policy.
The employee maintaining a capacity tracker should not automatically own resource allocation.
Leadership should identify one role accountable for:
- the quality of the decision;
- the business rules behind it;
- review of exceptions;
- changes to the policy;
- ensuring the supporting process remains reliable.
Technical maintenance and business accountability should not be confused.
7. Define exception authority explicitly
Exceptions are often where hidden decision systems become most dependent on individuals.
Someone knows that one customer can receive a lower margin.
Another employee knows that a certain product category uses a different commission calculation.
A manager knows that one project should be excluded from the normal capacity rule.
If these decisions are legitimate, make them governable.
Define:
- what qualifies as an exception;
- who can approve it;
- what information is required;
- whether approval expires;
- where the reason is recorded;
- when repeated exceptions should trigger a policy review.
A recurring exception that nobody reviews eventually becomes an unofficial rule.
8. Establish the source of truth for every important input
A decision system is only as reliable as the information entering it.
For each critical field, determine where the authoritative value should come from.
Customer terms may belong in the CRM.
Actual costs may belong in the finance system.
Employee availability may belong in a resource-management system.
Inventory should come from the operational system that owns inventory.
A spreadsheet may combine these values for analysis.
It should not quietly become an alternative master record unless leadership has intentionally designed it that way.
9. Make the decision reproducible
A mature decision process should survive a change in personnel.
Another qualified person should be able to determine:
- what decision was required;
- which information was used;
- which normal rules applied;
- whether an exception occurred;
- who approved the outcome;
- why the final decision differed from the standard result, if applicable.
Reproducibility does not eliminate human judgment.
It makes that judgment visible.
10. Choose technology only after the operating logic is clear
Once the decision system is understood, the technical requirement becomes much easier to define.
The business may discover that it needs:
- stronger spreadsheet controls;
- a standardized shared model;
- better data integration;
- workflow automation;
- a dashboard connected to authoritative systems;
- an ERP or CRM workflow;
- a custom application;
- no new software at all.
Technology should solve the specific operational weakness.
It should not be selected simply because the existing spreadsheet looks old or complicated.
The goal is organizational ownership of the decision
A company has moved beyond dangerous spreadsheet dependency when an important decision no longer depends on undocumented knowledge hidden inside a particular file.
The business can explain:
- who owns the outcome;
- which information is trusted;
- which rules apply;
- where judgment is allowed;
- how exceptions are governed;
- how the final decision is recorded.
The spreadsheet may still exist.
The difference is that it has returned to being a tool.
The company—not the workbook—now owns the decision system.
Turn Hidden Decision Logic Into an Owned Business Process
Clarify the rules, owners, data sources, and exceptions behind the spreadsheets your teams depend on before those dependencies become harder to unwind.
Review Your Critical Decision SystemsKeep Analysis Flexible Without Making Operations Fragile
A company does not need to eliminate spreadsheets to reduce operational risk. The stronger approach is to keep spreadsheets where flexibility and analysis are valuable while moving critical ownership, rules, approvals, source data, and recurring decisions into visible operating processes. The tool can remain flexible without becoming the only place the business knows how to operate.
This distinction matters because spreadsheets are often useful precisely where formal systems are too rigid.
Finance may need to test several scenarios.
Operations may need to model changing capacity.
Leadership may want to compare investment assumptions.
Sales may need to evaluate a non-standard commercial opportunity.
Those are legitimate analytical needs.
The risk appears when temporary analysis becomes permanent operating logic without anyone deliberately deciding that it should.
Separate the analytical layer from the operating layer
An analytical tool helps people understand a situation.
An operating process determines what happens next.
They may use some of the same information, but they serve different purposes.
Consider a project-profitability model.
Finance may use a workbook to test how different staffing levels, rates, or delivery assumptions affect margin.
That analysis can remain flexible.
But the company should separately define:
- what counts as project revenue;
- which costs must be included;
- how profitability is officially measured;
- who owns the profitability decision;
- what threshold requires escalation.
The workbook can test scenarios without becoming the only place where company policy exists.
Keep assumptions editable, but make them visible
Scenario modelling depends on assumptions.
The problem is not that assumptions can change.
The problem is when nobody knows they changed.
For important models, leadership should be able to distinguish:
- actual values from estimated values;
- approved policies from planning assumptions;
- temporary overrides from permanent rules;
- current assumptions from historical ones.
This does not require excessive bureaucracy.
A simple assumption register, version note, approval record, or documented owner may be enough depending on the importance of the decision.
Do not confuse flexibility with lack of control
Some teams resist process discipline because they fear losing flexibility.
That creates a false choice.
The company does not have to choose between:
- a rigid system that cannot adapt;
- an uncontrolled spreadsheet that only one person understands.
A better operating design allows controlled flexibility.
Standard cases follow known rules.
Unusual cases trigger defined review.
Analysis remains flexible.
Business accountability remains stable.
Use spreadsheets for questions, not undocumented policy
A useful rule is to ask what the file is doing.
If it is helping answer:
“What happens if we change this assumption?”
that is analysis.
If it is silently answering:
“Who gets approved?”
“What price can we offer?”
“Which employee receives which commission?”
“Which project receives resources?”
then the file is performing part of an operating role.
That does not automatically mean it must be replaced.
It does mean leadership should treat the logic with the same seriousness as any other business process.
Protect the source data
Flexible analysis still depends on reliable inputs.
A model loses value when people spend more time questioning the source data than interpreting the result.
For recurring critical models, clarify:
- where each important input originates;
- whether the input is refreshed automatically or manually;
- how old the data may be before it becomes unreliable;
- who can change source values;
- how corrections are handled.
A spreadsheet can remain the analytical surface while authoritative systems continue to own the underlying data.
Reduce copying between files
Spreadsheet dependency becomes more fragile when employees repeatedly move data from one workbook to another.
One file contains sales forecasts.
Another contains costs.
A third contains staffing.
Someone creates a fourth workbook to combine them.
Every additional manual transfer introduces another opportunity for:
- stale information;
- mismatched definitions;
- incorrect copying;
- version confusion;
- missing updates.
When a recurring decision depends on repeated cross-file assembly, the business should consider whether integration, shared data, or a more structured system would reduce operational effort.
Build controls according to consequence
A planning spreadsheet used by one manager does not require the same controls as a workbook that determines employee compensation or major customer pricing.
Governance should match business impact.
For higher-consequence models, controls may include:
- named ownership;
- restricted editing permissions;
- documented formulas or decision rules;
- version control;
- change review;
- backup and recovery;
- exception approval;
- periodic validation.
The objective is proportional control, not administrative overhead.
Make the process visible outside the workbook
A well-designed process should be explainable without opening the file.
Leadership should be able to describe:
- what decision is being made;
- who owns it;
- what information is required;
- which normal rules apply;
- who handles exceptions;
- where the final outcome is recorded.
The spreadsheet can then remain a useful tool within the process rather than becoming the process itself.
Watch for workarounds after a new system is introduced
Replacing a spreadsheet with software does not guarantee that dependency has disappeared.
Employees may recreate the spreadsheet if the new system does not support how work actually happens.
Common warning signs include:
- exports from the new system immediately moving back into Excel;
- teams maintaining private trackers alongside the official application;
- manual calculations continuing outside the new workflow;
- managers relying on unofficial reports because the formal dashboard lacks context;
- employees creating workarounds for legitimate exceptions.
When that happens, the right question is not simply why employees refuse to use the system.
The company should ask which operational need the workaround is solving.
A spreadsheet is healthy when the business can outlive it
Useful analytical tools should be replaceable.
If leadership can explain the rules, identify the inputs, name the owner, reproduce the result, and continue operating without the original file, the spreadsheet is serving the company.
If losing the file means losing the process, the relationship has reversed.
Flexibility is valuable. Dependency is the risk.
What Does Hidden Spreadsheet Dependency Look Like in a Growing Company?
Hidden spreadsheet dependency often looks harmless until growth increases the number of people, decisions, and exceptions around it. A model that one experienced employee could manage manually becomes a bottleneck when several teams rely on its output, different versions appear, and leadership cannot easily explain the rules behind important commercial or operational decisions.
Consider a hypothetical 60-person professional services company.
This is an illustrative scenario, not a KSoft Technologies client case.
The company has grown steadily.
It serves more customers, runs more projects, and employs more delivery staff than it did two years earlier.
Revenue planning appears structured.
Project managers use a delivery platform.
Finance uses accounting software.
Sales works from a CRM.
Leadership has dashboards.
Yet one spreadsheet quietly connects several of the company's most important decisions.
The spreadsheet originally solved a real problem
When the company was smaller, the founder wanted a simple way to understand whether new projects were commercially attractive.
A finance manager built a workbook.
Sales entered:
- proposed project value;
- expected duration;
- estimated team requirements;
- subcontractor costs;
- expected discounts.
The workbook calculated an expected margin.
The founder reviewed the result before approving larger proposals.
At the time, the process was useful and understandable.
The workbook becomes more sophisticated as the business grows
New requirements appear.
Different employee grades have different cost assumptions.
Certain customers receive negotiated rates.
Some projects require travel.
Others use outside specialists.
A new service line follows a different margin expectation.
The finance manager adds formulas to handle each change.
The workbook becomes more useful.
It also becomes harder for anybody else to understand.
Sales begins using the output as pricing policy
The company never formally creates a detailed pricing policy.
Instead, Sales learns a practical rule:
run the opportunity through the spreadsheet.
If the result looks acceptable, continue.
If it does not, ask Finance or the founder.
The workbook has now moved beyond analysis.
It is influencing which deals the company accepts and at what price.
Operations begins depending on the same model
Project managers also need to know what staffing assumptions were used when the deal was sold.
They begin requesting copies of the pricing model.
Some create simplified versions for delivery planning.
Others add actual staffing information after the project begins.
The spreadsheet starts functioning as both:
- a pricing calculator;
- a delivery assumption record;
- a project profitability model.
One tool is now serving several operational purposes.
Multiple versions appear
Sales keeps a copy to prepare proposals quickly.
Finance maintains the original.
One project manager builds a version with additional utilization assumptions.
Another team creates a template for the new service line.
The differences seem small.
Then leadership notices that two teams are calculating project profitability differently.
Both believe their method is correct.
Neither is intentionally ignoring company policy.
The company never created one.
The finance manager becomes the interpreter
Questions increasingly return to the person who originally built the workbook.
Which cost rate should be used?
Should travel be included?
Does this customer's negotiated rate override the standard margin threshold?
How should a subcontractor-heavy project be treated?
Is the new service line calculated the same way?
The finance manager knows the answers because they remember why each part of the model was created.
Their memory has become part of the control system.
The founder remains involved because exceptions are unclear
Leadership wants to delegate more pricing authority.
But the rules are difficult to explain.
Normal cases can be calculated.
Exceptions still return to the founder.
A large strategic customer wants a discount.
A project has unusually high subcontractor costs.
Sales wants to accept a lower initial margin for a long-term account.
Without explicit exception rules, the founder remains the safest decision point.
The hidden spreadsheet dependency has now reinforced founder dependency.
Leadership initially believes the answer is new software
The company considers building a pricing application.
That seems logical.
But reviewing the current workflow reveals a deeper problem.
The company cannot yet answer:
- who owns pricing policy;
- how official project profitability is defined;
- which employee cost assumptions are authoritative;
- which margin thresholds apply to which services;
- who can approve commercial exceptions;
- whether delivery assumptions should change after a project is sold.
Building software at this point would force the development team to make operating decisions that leadership has not made.
The company separates three different processes
Instead of immediately replacing the workbook, leadership separates the logic into three operating needs.
First, commercial pricing.
Sales needs clear rules for normal pricing, discount authority, and escalation.
Second, delivery planning.
Operations needs an agreed record of what staffing and delivery assumptions were made when the project was sold.
Third, project profitability.
Finance needs one consistent definition for comparing actual commercial performance against the approved plan.
What looked like one complicated spreadsheet was actually three connected decision systems.
Ownership becomes explicit
Commercial leadership owns pricing policy.
Operations owns delivery capacity and resource planning.
Finance owns the financial definition of project profitability.
Leadership agrees on the small number of decisions that still require founder approval.
The finance manager remains an important subject-matter expert.
But they are no longer the unofficial owner of every rule simply because they built the workbook.
The business rules are documented before technology changes
Leadership extracts the important logic from the spreadsheet.
It documents:
- approved cost inputs;
- normal margin expectations;
- discount authority;
- exceptional approval conditions;
- project-planning inputs;
- the company's profitability definition.
Some calculations continue in spreadsheets during the transition.
The difference is that the company now owns the rules outside the workbook.
Technology can now solve a defined problem
Once the operating model is clear, technical decisions become easier.
Standard data can come directly from authoritative systems.
Pricing rules can be applied consistently.
Exceptions can follow an approval workflow.
Approved commercial assumptions can move into project setup.
Actual financial data can later be compared with the approved plan.
Whether the final solution uses existing software, integration, ERP functionality, or custom development is now a technical decision based on a known operating requirement.
The biggest improvement is not replacing Excel
The company may eventually use fewer spreadsheets.
That is not the most important result.
The significant change is that leadership can now explain:
- how pricing works;
- who owns it;
- how project assumptions move into delivery;
- how profitability is defined;
- who can authorize exceptions.
The organization can continue making those decisions even if the original workbook or its creator is unavailable.
The operational risk disappeared when the business took ownership of the logic—not simply when the logic moved to another tool.
Can an Internal Leader Fix the Dependency?
Yes. An internal leader can remove spreadsheet dependency when they have enough authority, time, cross-functional visibility, and process discipline to extract hidden decision logic, assign ownership, standardize rules, and coordinate the transition. Outside support becomes more relevant when the problem spans departments but no internal person can consistently own the redesign.
Discovering a risky spreadsheet does not automatically mean the company needs a new executive, consultant, or software project.
In many businesses, the right people already exist.
The real question is whether someone can take responsibility for turning hidden working knowledge into an operating process the organization owns.
Start by identifying the natural business owner
The person who built or maintains the spreadsheet is not automatically the right owner.
Ownership should follow the business decision.
For example:
- pricing policy may belong to commercial leadership;
- project profitability definitions may belong to Finance;
- resource allocation may belong to Operations;
- commission policy may belong to Sales leadership or Finance, depending on the company's structure;
- purchasing policy may belong to Operations, Procurement, or Finance according to established responsibilities.
The spreadsheet owner may remain an important subject-matter expert.
But business accountability should sit with the role authorized to maintain the policy and accept the consequences of the decision.
The internal owner needs authority to challenge the current process
Documenting the spreadsheet is not enough.
The owner may need to question why the process works the way it does.
That can mean asking:
- Why is this assumption still being used?
- Who approved this threshold?
- Why do two departments calculate the same metric differently?
- Why does this decision still require founder approval?
- Why are exceptions stored in someone's memory?
- Why is the same information copied between three files?
- Why does one employee have to interpret every unusual case?
Those questions can cross functional boundaries.
An employee who understands the spreadsheet but cannot challenge the surrounding process may be unable to remove the dependency.
Knowledge transfer is not the same as process redesign
A common response to key-person dependency is:
“Train somebody else.”
That may reduce immediate continuity risk.
But teaching two employees how to use an undocumented decision system does not make the system well governed.
The company may simply move from one expert to two experts.
A stronger internal fix should capture:
- why the process exists;
- what decision it supports;
- where each critical input comes from;
- which rules are official;
- which assumptions remain flexible;
- who owns exceptions;
- who is accountable for the final outcome.
The goal is organizational knowledge, not additional individual dependency.
Capacity matters as much as capability
A capable Operations Manager, Finance Leader, COO, CTO, or functional head may understand exactly what needs to change.
That does not mean they have enough time to change it.
Hidden-system cleanup often competes with daily responsibilities.
The same leader may already be dealing with:
- customer escalations;
- staffing issues;
- reporting deadlines;
- delivery problems;
- financial reviews;
- hiring;
- urgent leadership requests.
Process redesign is important but rarely urgent on a quiet day.
That is why it can remain unfinished until the dependency becomes a visible problem.
Before assigning the work internally, leadership should ask:
- What will this person stop doing to make room for the work?
- Can they coordinate several departments?
- Can they keep the redesign moving after the first workshop?
- Will urgent operational issues repeatedly displace the project?
- Can they stay involved through implementation and adoption?
Assigning responsibility without capacity creates another dependency.
Finance can fix financial logic, but not every cross-functional dependency
Many high-risk spreadsheets originate in Finance.
Finance may therefore be the natural owner of specific definitions, controls, and financial rules.
But the process may extend beyond Finance.
A profitability model may depend on:
- Sales pricing assumptions;
- Operations staffing decisions;
- project delivery data;
- HR cost information;
- customer contract terms.
Finance can clarify the financial methodology.
It may still need cooperation and decision ownership from several functions to redesign the full process.
Technology should not be asked to decide company policy
Another common approach is to hand the spreadsheet to the internal development or IT team and ask them to replace it.
Technical teams can make critical contributions.
They can evaluate:
- system architecture;
- integrations;
- data sources;
- access control;
- auditability;
- automation;
- performance;
- maintainability.
They should not have to infer fundamental business rules from formulas.
A developer should not have to decide:
- what margin is acceptable;
- which commercial exceptions are valid;
- how profitability should be defined;
- who has authority to approve a discount;
- which department owns the final decision.
Leadership should establish those rules before asking technology to encode them.
Internal improvement works best when four conditions are present
A company can evaluate whether an internal leader is positioned to solve the problem using four practical conditions.
- Authority: Can the leader question rules, ownership, and processes across the departments involved?
- Capacity: Do they have protected time to lead the redesign through completion?
- Visibility: Can they see the entire decision path rather than one department's portion?
- Continuity: Can they remain accountable through discovery, redesign, implementation, adoption, and review?
When all four are present, internal ownership may be the simplest and strongest option.
Outside operational support becomes relevant when ownership falls between departments
Fractional Integrator support may become useful when everyone recognizes the dependency but nobody can own the complete correction.
Common signals include:
- Finance owns the numbers but not the operational process;
- Operations understands the workflow but cannot change commercial rules;
- Technology is waiting for clear business requirements;
- several leaders disagree on which data source should be authoritative;
- the founder remains the final decision-maker for unresolved exceptions;
- process improvement repeatedly loses priority to daily work;
- nobody is accountable for connecting the departmental pieces.
In that situation, the gap is not spreadsheet expertise.
It is cross-functional execution ownership.
A Fractional Integrator should make internal ownership stronger
External operational support should not create permanent reliance on another person.
A useful engagement should help the organization establish clearer internal ownership.
That may include:
- identifying the highest-risk hidden decision systems;
- bringing the relevant leaders into one process review;
- clarifying decision ownership;
- extracting undocumented rules;
- separating normal cases from exceptions;
- defining authoritative data sources;
- coordinating operational and technical requirements;
- tracking unresolved decisions until ownership is established.
Over time, functional leaders should be able to maintain the system without depending on the Fractional Integrator for routine decisions.
Outside support may be unnecessary when the business already has an effective operator
A Fractional Integrator is not automatically necessary because a company has spreadsheet dependency.
Additional operational leadership may add little value when:
- a capable COO or Operations Leader already owns cross-functional execution;
- functional decision rights are clear;
- leadership can agree on policies without founder intervention;
- internal teams have capacity to redesign the process;
- technical and business teams already work effectively together;
- decision-system improvements are consistently completed.
In that case, the company should use the leadership structure it already has.
Outside support will not solve missing leadership decisions
Fractional support also has limits.
It is unlikely to solve the problem effectively when:
- leadership cannot agree on basic priorities;
- nobody will accept accountability for the decision;
- the founder refuses to delegate any authority;
- departments refuse to share information;
- the business process is changing too rapidly to standardize;
- the only problem is that a straightforward spreadsheet needs technical cleanup;
- the company mainly needs software implementation rather than operational coordination.
An external operator can coordinate decisions.
They cannot manufacture leadership agreement where none exists.
Decide what capability is actually missing
“We need to replace this spreadsheet” can describe several very different needs.
The company may need:
- Process documentation because important knowledge is undocumented;
- Business ownership because nobody is accountable for the decision;
- Operational redesign because the workflow contains unnecessary manual steps;
- Data integration because information is copied between systems;
- Technical implementation because a clear process needs better software support;
- Fractional operational leadership because the problem crosses functions and nobody can drive the complete change.
These needs should not be treated as interchangeable.
A software project cannot solve missing ownership.
A Fractional Integrator cannot replace necessary technical development.
Documentation alone cannot fix a poorly designed rule.
The right intervention depends on what the dependency is actually hiding.
The internal-versus-fractional decision is an ownership test
Leadership does not need to begin by asking:
“Do we need a Fractional Integrator?”
A more useful question is:
“Who has the authority, capacity, and cross-functional responsibility to move this critical decision out of one person's file and into an operating process the company can own?”
If a clear internal answer already exists, empower that person and protect the time required to complete the work.
If every department owns only part of the problem and the founder remains the default integrator, the ownership gap itself deserves attention.
Move Critical Decisions Into the Operating System
A business becomes less fragile when critical decisions no longer depend on one spreadsheet, one dashboard, one document, or one person's memory. The goal is not to eliminate flexible tools. It is to make ownership, inputs, rules, exceptions, and decision history visible enough that the company can continue operating when people, systems, or circumstances change.
That is the real transition.
Not from Excel to software.
From hidden logic to organizational ownership.
Start with the decisions that would hurt most if they were wrong
Most companies have too many spreadsheets to review all of them at once.
Prioritize based on business consequence.
Begin with files or informal processes that influence:
- customer pricing;
- project profitability;
- employee commissions;
- purchasing;
- inventory;
- resource allocation;
- cash planning;
- customer commitments;
- major operational approvals.
These decisions deserve attention because mistakes can affect more than administrative efficiency.
They can change commercial outcomes, delivery obligations, employee compensation, or financial performance.
Ask one uncomfortable question about every critical spreadsheet
For each important file, ask:
“What does this spreadsheet know about our business that the business itself has never formally documented?”
The answer may reveal:
- undocumented approval thresholds;
- hidden pricing assumptions;
- unofficial customer exceptions;
- manually adjusted cost logic;
- capacity rules;
- department-specific definitions;
- workarounds created years ago;
- knowledge that exists only with one employee.
That information is the real asset.
The workbook is only where it currently lives.
Document rules at the business level
Important logic should be understandable without reading formulas cell by cell.
Leadership should be able to explain a decision rule in normal business language.
For example:
Instead of:
“Use the formula on the Margin V7 tab.”
the business should be able to say:
“Standard projects below the approved commercial threshold require review by the designated commercial owner.”
The technical implementation may remain complex.
The business rule should not be.
Decide where the official truth lives
Hidden decision systems become harder to control when several files contain different versions of the same information.
Leadership should determine where authoritative information belongs.
For each important data element, define:
- the source system;
- the accountable owner;
- who can change the value;
- how downstream tools receive updates;
- how errors are corrected.
A spreadsheet may still display or analyze the data.
It should not quietly become a competing source of truth.
Make normal decisions routine
Leadership time should not be consumed by decisions that happen repeatedly under predictable conditions.
Once normal rules are clear, routine cases should move through the business with less interpretation.
For example:
- standard discounts can follow defined authority levels;
- routine purchases can follow approved thresholds;
- normal commission calculations can follow an agreed policy;
- standard resource requests can follow visible allocation rules;
- common customer commitments can use current capacity information.
Human judgment remains available where it adds value.
It no longer needs to be recreated for every normal case.
Make exceptions more visible than normal work
Mature operating systems do not pretend exceptions will disappear.
They make them visible.
An exception process should clarify:
- what rule could not be followed;
- why the exception is necessary;
- who has authority to approve it;
- what decision was made;
- whether the exception should influence future policy.
This turns exceptions into useful operating information instead of private knowledge.
Remove founder dependency from routine decisions
Hidden spreadsheets and founder dependency often reinforce each other.
The rules are unclear, so employees escalate.
The founder answers.
Because the founder answers, nobody formalizes the rule.
The next similar case returns to the founder.
Breaking that cycle requires more than asking employees to “take ownership.”
Leaders need:
- clear decision rights;
- known boundaries;
- trusted data;
- documented normal rules;
- defined escalation conditions.
Delegation becomes safer when the operating system tells people where their authority begins and ends.
Automate only the parts the business understands
Once decision logic is clear, automation becomes much more useful.
Technology may be able to:
- retrieve data from authoritative sources;
- validate required information;
- apply standard calculations;
- route approvals;
- record exceptions;
- create an audit history;
- update downstream systems;
- provide leadership visibility.
Automation should reduce dependence on memory and repetitive coordination.
It should not freeze poorly understood logic into software.
Do not assume custom software is always the destination
After mapping the decision system, the company may discover that the existing spreadsheet can remain.
Perhaps the real improvement is:
- clearer documentation;
- stronger ownership;
- better source data;
- fewer duplicate copies;
- controlled editing;
- a formal exception process.
In another case, the company may need integration, ERP functionality, workflow automation, or custom development.
The solution should follow the operating requirement.
The operating requirement should not be invented to justify a technology project.
Treat new spreadsheets as signals
Spreadsheets frequently appear where existing systems do not answer an operational need quickly enough.
That makes them useful diagnostic signals.
When a new critical workbook becomes widely used, leadership should ask:
- What gap is this file solving?
- Is the need temporary or recurring?
- Does the file contain new business rules?
- Is it replacing functionality missing from an existing system?
- Will other departments eventually depend on it?
- Who owns it if it becomes permanent?
The earlier those questions are asked, the less likely a temporary workaround is to become invisible infrastructure.
Review the decision system when the business changes
A well-designed rule can become outdated.
Pricing changes.
Cost structures change.
Customer segments change.
Teams reorganize.
New services are launched.
Authority levels change.
Systems are replaced.
Process owners should periodically review:
- whether the rule still reflects current business policy;
- whether source data remains reliable;
- whether exceptions are increasing;
- whether teams have created new workarounds;
- whether one employee has again become indispensable;
- whether the technology still supports the operating process.
Ownership is ongoing.
A process does not remain healthy simply because it was documented once.
Test whether the business owns the decision
A practical review can use six questions:
- Can we name one accountable owner?
- Can we identify the authoritative inputs?
- Can we explain the normal rule without opening the spreadsheet?
- Can we identify who may approve an exception?
- Can another qualified person reproduce the decision?
- Can we explain later why the decision was made?
A “no” does not automatically mean the process needs software.
It means part of the decision system still needs operational clarification.
The spreadsheet is not the real warning
A sophisticated company can use thousands of spreadsheets and still operate with strong controls.
Another company can rely on one workbook and carry substantial operational risk.
The difference is whether the organization owns the logic.
If pricing rules exist only as formulas, the workbook owns part of the pricing process.
If profitability definitions exist only in one analyst's model, the analyst's working knowledge owns part of financial governance.
If resource allocation requires one manager to interpret a private tracker, that person's memory owns part of the operating system.
The solution is not a campaign against spreadsheets.
It is disciplined ownership of critical business decisions.
Your company should be able to lose a file without losing its ability to explain how an important decision is supposed to work.
Pick one critical spreadsheet this week.
Do not begin by asking how to replace it.
Ask what decisions it controls, what rules it contains, which assumptions it hides, who depends on it, and who should actually own the process.
That conversation usually reveals whether you have a useful analytical tool—or an undocumented operating system.
Frequently Asked Questions
When does a spreadsheet become an operational risk?
A spreadsheet becomes an operational risk when important decisions depend on logic, assumptions, or manual adjustments that are difficult to reproduce outside the file. The risk is higher when only one person understands the model, multiple versions exist, or leadership cannot clearly explain the rules behind the output.
Why is key-person dependency dangerous in business decision-making?
Key-person dependency is risky because critical decisions may stop, slow down, or become inconsistent when the knowledgeable employee is unavailable. The deeper problem is usually not the person but the undocumented business logic they carry. Important rules, assumptions, and exceptions should belong to the organization rather than remain in individual memory.
How can a company tell whether a spreadsheet is supporting a process or running it?
A spreadsheet is supporting a process when ownership, rules, data sources, and decision authority are already clear outside the file. It is effectively running the process when employees cannot make or explain the decision without opening that particular workbook or asking the person who understands how it works.
Should companies replace every important spreadsheet with software?
No. Spreadsheets remain useful for analysis, forecasting, modelling, and changing scenarios. Replacement becomes more relevant when a recurring operational decision requires stronger controls, shared data, automation, auditability, or cross-functional access. The correct solution may be better governance, integration, an existing business system, or custom software depending on the actual need.
What should be documented before replacing a critical spreadsheet?
Document the decision the spreadsheet supports, accountable owner, authoritative inputs, normal business rules, assumptions, exception conditions, approval authority, and required output. The company should also understand how data enters and leaves the process. This prevents a technology team from having to infer business policy directly from formulas and historical workarounds.
How should spreadsheet exceptions and manual overrides be handled?
Exceptions should have defined conditions, an authorized decision-maker, a recorded reason, and a clear escalation path. Repeated overrides should also be reviewed to determine whether the official rule is outdated. An exception that occurs frequently but remains undocumented can quietly become an unofficial business policy without leadership realizing it.
What does a Fractional Integrator do with hidden spreadsheet dependencies?
A Fractional Integrator can help leadership identify the decision behind the spreadsheet, clarify cross-functional ownership, surface undocumented rules, define exception responsibilities, and coordinate operational requirements across departments. The role does not simply replace the file; it helps the company move critical decision logic into a process the organization can understand and maintain.
Is a Fractional Integrator the same as an IT consultant or software developer?
No. A Fractional Integrator primarily focuses on cross-functional execution, accountability, ownership, and operating processes. IT consultants or software developers focus more directly on technical architecture, integrations, security, data, or implementation. Both may be needed when a hidden business process must first be clarified and then supported with technology.
Can an internal operations or finance leader fix spreadsheet dependency?
Yes, when the internal leader has enough authority, time, visibility, and cross-functional support to redesign the full decision process. They must be able to clarify ownership, challenge outdated rules, coordinate departments, and remain accountable through implementation. Outside support is unnecessary when a capable internal operator already owns that work effectively.
When should a company consider outside operational support?
Outside operational support may be useful when the dependency crosses several departments and no internal leader can consistently own the correction. Typical signals include conflicting definitions, unclear decision rights, founder escalation, stalled system projects, repeated exceptions, and technical teams waiting for business rules that leadership has not formally resolved.
How much does it cost to replace or redesign a spreadsheet-based decision system?
Cost depends on what the company actually needs. Process documentation, operational redesign, data integration, ERP configuration, custom software, and Fractional Integrator support have very different scopes. Pricing cannot be determined from the spreadsheet alone; the business first needs to define the decision, complexity, systems involved, ownership gaps, and implementation requirements.
What is the first step a leadership team should take with a critical spreadsheet?
Start by choosing one high-consequence spreadsheet and asking what business decision it controls. Then identify the owner, source data, embedded rules, assumptions, exceptions, and people required to make the process work. Do not begin with software selection. First determine what operational knowledge the company needs to own outside the file.