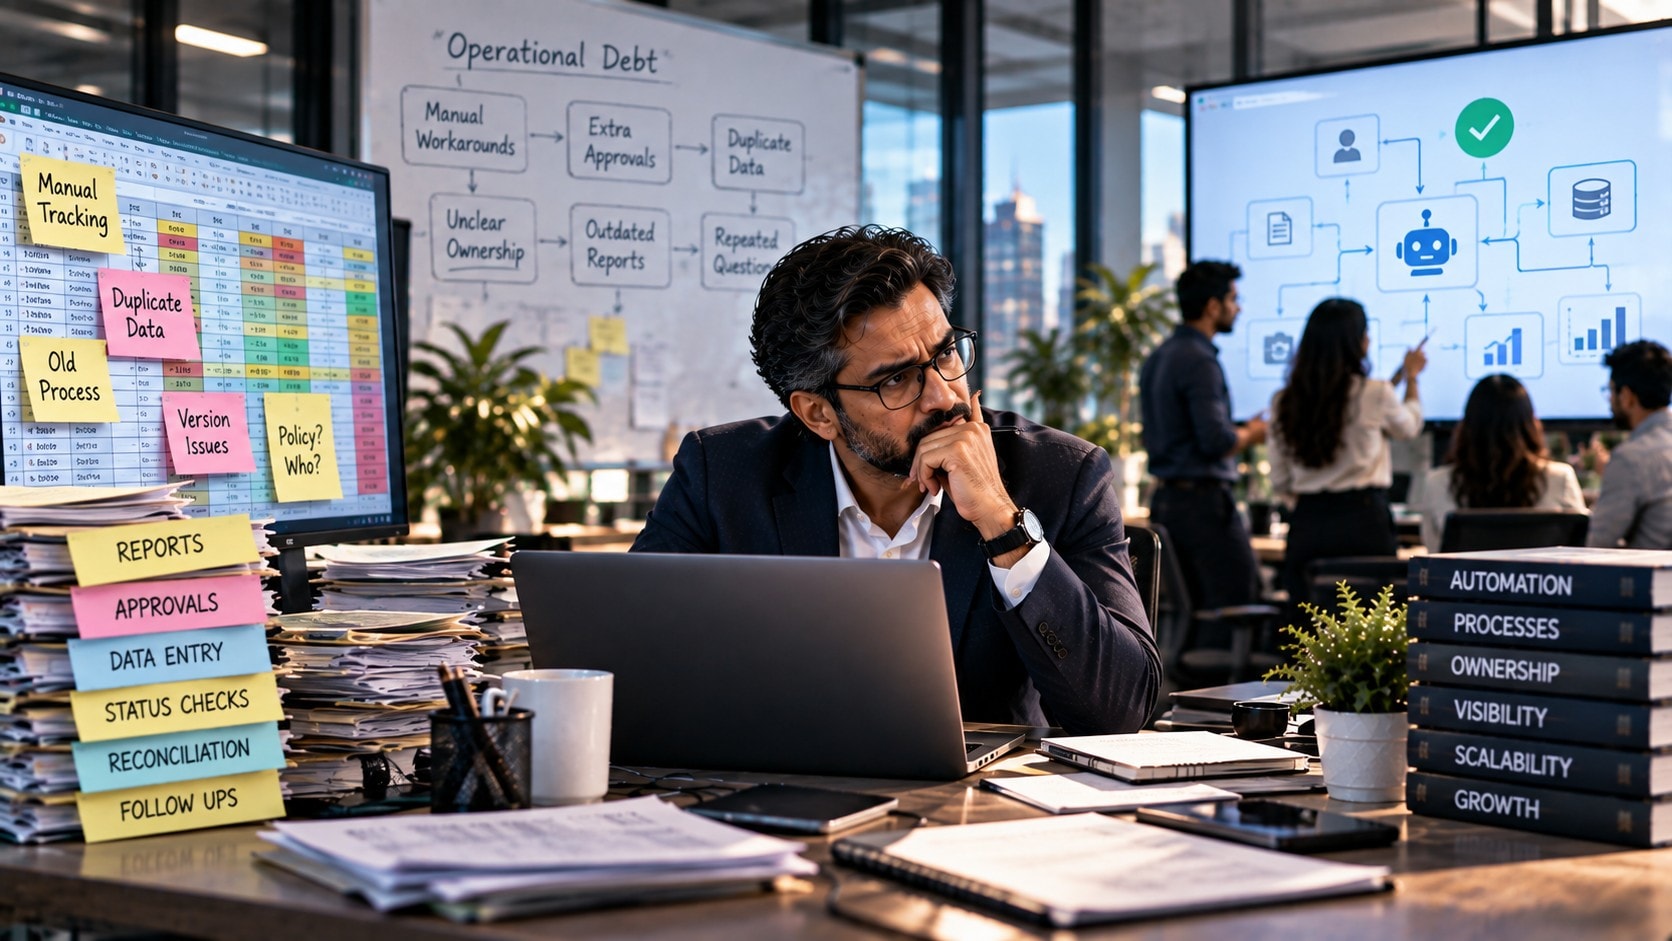
Old approvals, repeated checks, duplicate entry, unnecessary reports, and inherited workarounds can quietly become permanent operating costs. The challenge is identifying which processes still create value and which ones the business is simply carrying forward.
Engineering teams have a useful habit: when a shortcut makes future change harder, they give the problem a name. Operations rarely gets the same clarity. An extra approval, a manual reconciliation, a duplicate spreadsheet update, or an old reporting step can survive for years without anyone calling it operational debt.
The process usually still works. That is what makes the debt difficult to see. Employees compensate for it, managers remember the exceptions, and experienced people know which steps can be skipped when something is urgent. What looks like normal execution may actually depend on repeated effort that the company no longer needs.
Growth makes the cost harder to hide. A five-minute manual check performed occasionally can become hours of recurring work when transaction volume rises. One approval added after an old incident can turn into a permanent queue. A report created for a former executive may continue consuming employee time long after anyone uses it to make a decision.
Paying down operational debt does not mean automating everything or rewriting every process. It means identifying work that exists because of history rather than current business need, calculating what that work repeatedly consumes, and deliberately deciding what to remove, simplify, standardize, automate, or retain.
What Is Operational Debt—and Why Does It Keep Compounding?
Operational debt is the recurring burden created when temporary workarounds, outdated rules, unnecessary controls, manual handoffs, or poorly designed processes remain in use after their original purpose has changed or disappeared. Like technical debt, it increases the effort required to change, scale, or reliably operate the business.
Most operational debt begins for a reasonable reason.
A customer problem leads to an additional approval.
A system limitation forces an employee to maintain a spreadsheet.
A reporting error results in a second manual check.
A manager asks for a weekly report because visibility is poor.
Two systems cannot exchange information, so someone copies the same data into both.
None of those responses is necessarily wrong at the time.
The debt appears when the company changes but the workaround remains.
Temporary controls quietly become permanent work
Imagine a business introduces a second approval after one expensive purchasing mistake.
Six months later, the original issue has been solved. Purchasing rules are clearer. The team is more experienced. The underlying system now validates the critical information.
But nobody removes the extra approval.
Every purchase still waits for two people.
The business continues paying for yesterday's risk through today's operating time.
That is a common form of operational debt.
Small process costs repeat more often than leaders realize
One unnecessary step rarely looks serious in isolation.
The cost comes from repetition.
A manual check might consume only a few minutes.
A duplicate data entry step may feel routine.
A weekly report might take one employee half an hour.
An approval may delay work only slightly.
But repeated across customers, orders, projects, employees, departments, and months, these steps absorb capacity without creating equivalent business value.
Operational debt also creates change friction
The cost is not limited to employee time.
Old processes make new processes harder to introduce.
A workflow cannot be automated cleanly because several undocumented exceptions exist.
A new employee cannot follow the written process because experienced staff use unofficial shortcuts.
A system implementation becomes larger because the company tries to reproduce every historical step.
A manager cannot remove a report because nobody remembers who originally requested it.
Debt therefore reduces operational flexibility. Every inherited step becomes something leadership must understand, preserve, challenge, or unwind before the business can change safely.
A process should not earn permanent status simply because the company has repeated it for a long time.
When “The Way We Work” Becomes the Problem
Operational debt becomes difficult to remove when employees stop seeing individual workarounds as temporary. The extra approval, reconciliation, report, spreadsheet, or manual check becomes part of institutional memory. New employees inherit it, managers plan around it, and eventually the organization treats historical process design as though it were a current business requirement.
Familiarity can hide unnecessary work
Ask an experienced employee why a step exists and the answer may be:
“We have always done it this way.”
That answer is useful.
It signals that the process may no longer have an active owner who can explain its purpose.
The step might still be necessary.
But leadership should be able to identify:
- the risk or outcome the step controls;
- the person accountable for that control;
- whether the original condition still exists;
- whether another system or process now performs the same function;
- what would happen if the step disappeared.
If nobody can answer those questions, repetition has replaced process ownership.
Manual checks often survive after the reason for them disappears
Manual verification is sometimes essential.
It becomes debt when people continue checking information that is already validated elsewhere.
One employee enters customer information.
Another employee checks the same fields.
A manager reviews them again before approval.
The organization may describe the process as careful.
But if the checks do not catch meaningfully different risks, the business may simply be paying several times for the same control.
Duplicate data entry creates invisible coordination cost
When systems do not share information, employees become the integration layer.
A sales record is copied into an operations tracker.
Project information moves into a finance spreadsheet.
Customer status is updated in a reporting file.
The work feels administrative, but its cost goes beyond typing.
Every duplicate entry creates another place that can become outdated, another reconciliation task, and another question about which version is correct.
Reports can outlive the decisions they were created to support
A report should help somebody make, monitor, or verify a decision.
When nobody can identify that decision, the report deserves review.
Growing companies often accumulate reporting because adding a report is easier than removing one.
A leader asks for visibility.
The team creates a spreadsheet or dashboard.
The leader's needs later change, but the reporting routine remains on someone's calendar.
Operational debt survives because stopping established work can feel riskier than continuing it.
Workarounds deserve an expiration date
A workaround is not automatically a bad process.
Sometimes the fastest responsible response is temporary manual work.
The mistake is allowing temporary work to become permanent without review.
Whenever a workaround is introduced, leadership should ideally know:
- why it exists;
- who owns it;
- which condition would allow it to be removed;
- when it will be reviewed;
- whether its recurring cost is still justified.
That creates a simple operational discipline: temporary fixes stay temporary unless someone deliberately decides otherwise.
The dangerous process is not always the visibly broken one. It is often the process everyone has become too accustomed to questioning.
How Much Old Process Is Your Team Still Carrying?
Review the approvals, checks, reports, handoffs, and workarounds that consume recurring effort without a clear current owner or business purpose.
Assess Your Operational DebtWhere Is Operational Debt Hiding in Your Business?
Operational debt usually hides inside work that feels ordinary: approvals nobody questions, checks repeated by several people, information copied between systems, reports that no longer drive decisions, manual follow-ups, undocumented exceptions, and workflows that depend on one experienced employee knowing what to do next.
The hardest debt to identify is rarely the process everyone agrees is broken.
Broken processes attract attention.
Operational debt often survives because the process still functions.
Employees compensate for it.
Managers build schedules around it.
New hires are trained to repeat it.
Eventually, nobody remembers which parts were intentional and which parts were temporary fixes.
Approvals are one of the easiest places for debt to accumulate
Approvals usually begin as controls.
Leadership wants to prevent an expensive mistake, protect cash, maintain quality, or create oversight.
The problem is that approval layers are easier to add than remove.
A process that originally needed one decision-maker may gradually require:
- a team lead review;
- a department manager approval;
- Finance confirmation;
- an executive sign-off.
Leadership should ask what independent risk each approval controls.
If two people are checking the same condition without adding a different judgment, the business may be carrying duplicate control rather than stronger governance.
Look for employees checking what systems already validate
Manual verification often remains after technology improves.
A system now prevents incomplete submissions, but someone still reviews every record for missing fields.
An application validates a calculation, but an employee recalculates it manually “just to make sure.”
A workflow prevents unauthorized actions, but a second person still checks the same permission before work continues.
Some secondary checks remain necessary.
Others survive because nobody formally removed the old control when the new one was introduced.
The correct question is not:
“Can we remove this check?”
It is:
“What specific failure does this check prevent today, and is another control already preventing the same failure?”
Duplicate entry is often evidence of system debt and process debt at the same time
An employee enters customer information into the CRM.
Operations re-enters it into a tracker.
Finance copies part of it into another sheet.
Management receives a summary created from all three.
The company may describe these as separate administrative tasks.
Operationally, they are one information flow being recreated several times.
This debt produces more than extra typing.
It creates:
- inconsistent records;
- reconciliation work;
- uncertainty about the latest value;
- delayed updates;
- additional training requirements;
- more places where an error can enter the process.
If several teams maintain their own version of the same fact, the company should review both its systems and its process ownership.
Reports can become recurring debt when nobody owns the decision they support
A recurring report should have a recurring purpose.
Someone should be using it to:
- make a decision;
- identify an exception;
- monitor an agreed threshold;
- allocate resources;
- verify a business outcome.
If a team spends time preparing a report but nobody can name the decision that changes because of it, that report is a strong operational-debt candidate.
Another warning sign is a report that produces another report.
An analyst prepares detailed numbers.
A manager reformats them.
Another leader extracts a smaller summary.
The executive team then asks for a separate dashboard.
Each layer may have developed for a reason, but the business should periodically check whether the full reporting chain is still necessary.
Status chasing is operational debt disguised as communication
Some processes work only because people repeatedly ask one another what is happening.
“Has this been approved?”
“Did the customer send the document?”
“Has Finance processed it?”
“Who has the task now?”
“Is this ready for delivery?”
Communication itself is not the problem.
The debt appears when routine status information requires human investigation every time.
Repeated status chasing usually points to one or more structural gaps:
- unclear ownership;
- invisible workflow stages;
- missing notifications;
- inconsistent status definitions;
- information spread across several systems;
- no agreed place to see current progress.
If people must ask for the same type of status every day, the company should examine the workflow rather than simply improving the reminder message.
Handoffs accumulate debt when nobody owns the space between departments
Many operational problems do not exist inside a department.
They exist between departments.
Sales finishes its work.
Operations is waiting for information.
Finance needs a field Sales does not normally capture.
Delivery assumes someone else confirmed the customer requirement.
Every team may be performing its individual responsibility correctly while the overall process remains inefficient.
Cross-functional debt often shows up as:
- repeated clarification emails;
- missing information at handoff;
- duplicate approval;
- tasks waiting without a visible owner;
- different definitions of “complete”;
- managers resolving the same coordination problem repeatedly.
Department-level optimization will not fully fix a workflow whose debt sits between functions.
One-person knowledge is a form of operational debt
Experienced employees often make weak processes look stronger than they are.
They remember which customer is an exception.
They know which report needs a manual correction.
They know whom to call when an approval stalls.
They can recognize a mistake before it becomes visible to anyone else.
That expertise is valuable.
The debt appears when the process works only because that expertise compensates for missing rules, documentation, ownership, or system visibility.
A useful test is:
If this person were unavailable for two weeks, which routine workflows would suddenly become slower, riskier, or harder to explain?
The answer often reveals operational debt leadership has normalized.
Exception processes deserve more attention than normal workflows
Standard processes are usually documented.
Exceptions are where operational memory takes over.
A customer needs a non-standard contract.
A project requires unusual pricing.
A vendor cannot follow the normal purchasing flow.
An employee needs an urgent approval.
One exception is manageable.
The problem begins when similar exceptions appear repeatedly but the company continues treating each one as unique.
Repeated exceptions may indicate:
- an outdated policy;
- an incomplete standard process;
- unclear authority;
- missing system functionality;
- a business model that has evolved faster than its operating rules.
Recurring exceptions should create process-learning opportunities, not permanent manual work.
Use a process-debt audit instead of asking employees what is inefficient
Employees may struggle to identify debt they have worked around for years.
A more useful audit is to examine recurring workflows and ask:
- Purpose: Why does this step exist?
- Owner: Who is accountable for keeping or removing it?
- Trigger: What originally caused the step to be introduced?
- Frequency: How often is the step performed?
- Effort: How much human time does it consume each time?
- Dependency: What people, spreadsheets, emails, or systems does it depend on?
- Control: What risk or outcome does it protect?
- Duplication: Is another step already performing the same function?
- Expiration: What would need to be true for this step to disappear?
This shifts the conversation from vague frustration to specific operating decisions.
The objective is not to find processes employees dislike.
It is to find recurring work whose present cost is no longer justified by its present value.
How Much Is Operational Debt Really Costing You?
Measure operational debt by looking beyond the time required for one unnecessary step. Its real cost includes repetition, waiting time, rework, management attention, errors, training complexity, and the effort required to change the process later. A small inefficiency can become expensive when it occurs frequently or blocks several people.
Leadership often notices operational debt only when it creates a visible failure.
But many forms of debt never create one dramatic incident.
They simply consume capacity every week.
That makes measurement important.
Start with recurring human effort
The simplest cost is the time employees spend performing the unnecessary or outdated step.
For a recurring activity, estimate:
Time per occurrence × number of occurrences × number of people involved.
Then apply the organization's appropriate internal labor-cost method if leadership wants a financial estimate.
For example, a manual check that appears trivial may deserve attention if it happens across hundreds of transactions.
Conversely, a cumbersome process used twice a year may not be the highest priority.
Frequency changes the economics.
Measure waiting time separately from working time
A process can consume five minutes of labor and still delay the business for two days.
That happens when work sits:
- in an approval queue;
- waiting for missing information;
- with a manager who did not know action was required;
- between two departments;
- while someone searches for the correct file;
- until the one knowledgeable employee becomes available.
Queue time and labor time are different costs.
If leadership measures only minutes of employee effort, it may miss the process debt affecting customer response, project starts, purchasing, billing, hiring, or delivery.
Include rework created by unclear or duplicated processes
Operational debt often creates work twice.
Information is entered incorrectly and then corrected.
A request reaches the wrong approver and is rerouted.
One department completes a form that another department recreates.
A report is generated from outdated data and must be rebuilt.
A customer is asked for information the company already holds elsewhere.
Rework should be measured separately because it reveals process failure rather than simply process effort.
Management attention is often the most expensive hidden cost
Weak processes pull managers into routine coordination.
They chase approvals.
Resolve handoff confusion.
Reconcile conflicting information.
Approve low-risk exceptions.
Explain old rules.
Answer status questions employees should be able to resolve without them.
That creates an important diagnostic question:
How much management time is being used to keep routine work moving?
When senior people repeatedly intervene in predictable workflows, the organization is paying a leadership premium for unresolved operational debt.
Founder involvement is another measurable signal
In founder-led companies, debt often hides inside escalations.
A policy is unclear, so the founder decides.
An exception has no owner, so the founder approves it.
Two departments disagree, so the founder resolves the handoff.
Nobody knows whether an old step can be removed, so the founder is asked.
Individual decisions may take only minutes.
Together, they reveal a larger cost: the business is using founder attention as an operating-control mechanism.
Count the systems and files required to complete one workflow
Tool switching creates operational overhead even when each system works correctly.
A team member may need to:
- retrieve a request from email;
- check customer information in the CRM;
- update a spreadsheet;
- obtain approval through chat;
- enter the approved information into an accounting system;
- update another tracker so management can see the status.
The company may technically have all the systems it needs.
The process still carries integration debt because humans are responsible for connecting them.
Training complexity is part of the cost
Operational debt often appears in onboarding instructions.
“Use this system, but also update this sheet.”
“Normally this requires approval, except for these customers.”
“Ignore that report and use the one Finance sends on Friday.”
“If the status says complete, check with Operations because it may not actually be ready.”
Each workaround increases what a new employee must memorize before becoming independently effective.
A useful indicator is the gap between:
- how the formal process is documented;
- how experienced employees explain the process in practice.
The larger that gap becomes, the more institutional knowledge is being used to compensate for weak process design.
Change cost is part of operational debt too
Technical debt makes software harder to change.
Operational debt creates the same effect in business processes.
A company wants to introduce a new CRM workflow.
Then leadership discovers five spreadsheets depend on the old process.
A pricing policy needs to change.
But several teams maintain separate calculations.
A new approval system is introduced.
Employees continue using informal chat approvals because several exceptions were never designed into the new flow.
The difficulty of making a reasonable operational change is itself evidence of accumulated debt.
Not every inefficient step deserves immediate repayment
Once leadership starts looking, the list can become large.
Trying to fix every annoyance at once creates another improvement program that never finishes.
Prioritize operational debt using four factors:
- Frequency: How often does the debt create work?
- Cost: How much time, delay, rework, or management attention does it consume?
- Business impact: Does it affect customers, cash, delivery, compliance, or strategic execution?
- Removal effort: How difficult is it to simplify or eliminate?
High-frequency, high-impact debt that can be removed with modest effort is often a strong first target.
Create a simple operational-debt register
The business does not need a complicated accounting model.
A practical register can include:
| Field | Question | Why It Matters |
|---|---|---|
| Debt item | What recurring step or workaround are we reviewing? | Creates a specific improvement target |
| Original purpose | Why was it introduced? | Prevents removal of a still-valid control |
| Frequency | How often does it occur? | Shows how quickly small effort compounds |
| Human effort | Who is involved and for how long? | Reveals recurring capacity consumption |
| Delay | How much waiting does the step create? | Captures cost beyond labor time |
| Rework | Does the step create corrections or duplicate activity? | Identifies avoidable process failure |
| Owner | Who can decide whether the step changes? | Converts observation into accountability |
| Repayment action | Should we remove, simplify, standardize, automate, or retain it? | Creates a clear next decision |
This register changes the conversation.
Instead of saying:
“This process is annoying,”
leadership can say:
“This step occurs every day, involves three roles, creates a recurring approval queue, and no longer controls a unique risk.”
That is a much stronger basis for process change.
Measure debt to make better repayment decisions—not to create another report
There is an obvious irony in building a complicated measurement process for operational debt.
The purpose is not to calculate every minute with financial precision.
It is to make invisible recurring cost visible enough for leaders to prioritize.
If the cost of measuring the debt becomes larger than the debt itself, simplify the measurement.
Once leadership can see where recurring effort, delay, rework, and management attention are accumulating, the next step is to create a disciplined repayment system rather than fixing whichever process happens to be most frustrating that week.
A Practical Repayment System for Operational Debt
Operational debt should be repaid through a repeatable process: identify the recurring burden, confirm why it exists, measure its current cost, decide whether the underlying control is still necessary, assign an owner, and choose whether to remove, simplify, standardize, automate, or deliberately retain the process.
The important word is deliberately.
Companies accumulate debt when old processes continue by default.
They reduce debt when someone is explicitly responsible for deciding whether those processes still deserve to exist.
Step 1: Name the debt precisely
Avoid broad statements such as:
“Our approval process is inefficient.”
That is too vague to fix.
A stronger debt item would be:
“Every customer discount above the standard rate requires three approvals, although the first two approvers review the same margin threshold.”
Or:
“Operations re-enters customer and project information from the CRM into a spreadsheet before work can begin.”
Or:
“Finance prepares a weekly report that is manually reformatted by two managers before leadership reviews a subset of the same information.”
A clearly named debt item creates a clearly defined improvement target.
Step 2: Recover the original reason
Do not remove a process simply because nobody likes it.
First understand why it was introduced.
The approval may protect a real financial risk.
The manual check may exist because a system previously produced unreliable data.
The duplicate report may have been created because two departments used different definitions.
The workaround may protect a customer requirement that is not obvious to the rest of the organization.
Ask:
- What problem was this step designed to prevent?
- Who introduced it?
- What was happening in the business at the time?
- Does that condition still exist?
- Has another control replaced its purpose?
This protects the company from removing controls whose value is simply poorly documented.
Step 3: Measure the recurring burden
Estimate enough cost to prioritize intelligently.
Useful measures include:
- occurrences per week or month;
- employee time per occurrence;
- number of people involved;
- average waiting time;
- amount of rework created;
- frequency of management escalation;
- impact on customer or delivery timelines.
The estimate does not need to become an accounting exercise.
It needs to answer one practical question:
Is the recurring cost of this process still justified by the value or risk control it provides?
Step 4: Separate the control from the current implementation
This is one of the most important steps.
A control may still be necessary even when the way the company performs it is outdated.
For example, the business may genuinely need to prevent unauthorized discounts.
That does not automatically mean three manual approvals are necessary.
The requirement is:
protect pricing authority.
The current implementation is:
three people checking the request.
Once leadership separates those two ideas, better options become possible.
The company might use:
- predefined approval thresholds;
- role-based authority;
- automated validation;
- exception routing;
- periodic audit rather than transaction-by-transaction review.
Preserve the business control while challenging the inherited mechanism.
Step 5: Choose one of five repayment actions
Every debt item should end in a deliberate decision.
A useful five-way classification is:
- Remove: The step no longer serves a valid purpose.
- Simplify: The purpose remains valid, but the workflow contains unnecessary effort.
- Standardize: Different teams perform the same work inconsistently.
- Automate: The process is stable, repeatable, rule-based, and worth reducing manually.
- Retain: The current process still provides enough value to justify its cost.
“Retain” is a valid outcome.
Debt repayment is not a campaign to remove every manual step.
It is a method for ensuring recurring work exists for a current reason.
Step 6: Assign one owner to the repayment decision
Cross-functional debt often survives because everybody is affected but nobody owns the whole process.
Sales experiences the delay.
Operations performs the workaround.
Finance owns one approval.
Technology owns the system involved.
The founder resolves the exceptions.
Improvement stalls because no single person is accountable for the end-to-end outcome.
Every repayment item needs one named owner responsible for:
- validating the problem;
- bringing the required functions together;
- obtaining necessary decisions;
- coordinating implementation;
- confirming the old process actually stops.
Multiple contributors are normal.
Multiple accountable owners usually are not.
Step 7: Design the future process before buying technology
Software should support the process the company wants to operate.
It should not automatically reproduce the process the company inherited.
Before automating a debt item, define:
- the trigger;
- required information;
- normal workflow;
- decision owner;
- approval limits;
- exception paths;
- successful completion;
- required visibility.
If those elements remain unclear, the organization is not yet ready to encode the process into technology.
Step 8: Remove the old process when the new one starts
Operational debt can survive a successful improvement project.
A company introduces a new workflow but keeps the old spreadsheet “for backup.”
Employees continue sending the old email notification because they do not fully trust the new system.
Managers maintain the previous report alongside the new dashboard.
Soon the organization has both the old process and the new one.
Debt has increased rather than decreased.
Every process change should include a retirement decision:
- Which old step stops?
- Which file is archived?
- Which report is discontinued?
- Which approval is removed?
- Which responsibility changes?
- Who confirms that parallel work has ended?
Implementation is incomplete while employees are expected to maintain two operating systems.
Step 9: Measure whether the debt actually disappeared
A completed project does not necessarily mean the operating burden is gone.
Review the process after implementation.
Compare:
- human effort before and after;
- waiting time before and after;
- number of handoffs;
- number of manual entries;
- exception volume;
- manager intervention;
- rework.
If employees have created new workarounds around the improved process, investigate why.
A workaround is feedback.
It may indicate the redesigned system overlooked a legitimate operating need.
Step 10: Put debt review into the operating rhythm
Operational debt will return.
Businesses change too quickly for every process to remain optimal forever.
The goal is not zero debt.
The goal is to prevent debt from becoming invisible.
Leadership can periodically review:
- recurring manual work;
- new workarounds;
- repeated exceptions;
- approval queues;
- duplicated reporting;
- founder escalations;
- cross-functional handoff problems.
This turns operational debt from an occasional cleanup exercise into a manageable part of business execution.
Use a visible repayment backlog
A simple backlog keeps operational debt from disappearing behind urgent daily work.
Each item can record:
- the current process problem;
- estimated recurring cost;
- business impact;
- proposed repayment action;
- accountable owner;
- target review date;
- current status.
Leadership can then prioritize operational debt alongside other execution work instead of relying on whoever complains most loudly.
Operational debt becomes manageable when every recurring burden has a current reason, a visible cost, and an accountable owner.
Turn Process Friction Into a Prioritized Repayment Plan
Separate necessary controls from inherited work, assign clear ownership, and focus improvement effort on the operational debt that consumes the most recurring capacity.
Review Your Process PrioritiesWhat Does a Fractional Integrator Do About Operational Debt?
A Fractional Integrator helps leadership make operational debt visible across functions, identify which recurring processes are consuming unnecessary capacity, assign owners, force decisions on outdated work, and maintain a repayment rhythm. The role is especially useful when debt spans several departments and no internal leader owns the complete end-to-end process.
A Fractional Integrator does not simply walk through the company deleting steps.
The role is more useful when it creates a disciplined way for functional leaders to challenge, redesign, and own the operating system together.
Operational debt is often invisible from inside one department
Finance may see a necessary approval.
Sales sees a two-day delay.
Operations sees repeated status chasing.
Technology sees an integration limitation.
The founder sees another issue that requires intervention.
Every team sees one part of the same process.
A Fractional Integrator can help map the complete workflow and ask:
- Where does work enter?
- Which teams touch it?
- Where does it wait?
- Which information is entered more than once?
- Which approvals control unique risks?
- Which steps exist because of historical workarounds?
- Where does ownership become unclear?
- Where does the founder or senior management intervene?
That cross-functional view is often where the most valuable debt becomes visible.
The role challenges process inheritance
Long-standing workflows gain authority simply because they are familiar.
An experienced operator can help leadership challenge them without assuming they are wrong.
Useful questions include:
- What outcome does this step create?
- What risk does it control?
- Is that risk still present?
- Could the same control be achieved with less recurring effort?
- Why does this require executive attention?
- Why are two departments maintaining the same information?
- What would happen if this report stopped for a month?
The purpose is not arbitrary simplification.
It is to make each recurring activity justify its place in the current operating model.
A Fractional Integrator can make the repayment backlog executable
Many companies already know several processes need improvement.
The list is not the problem.
Execution is.
Improvement work competes with:
- customer issues;
- delivery deadlines;
- hiring;
- sales priorities;
- financial deadlines;
- urgent management requests.
A Fractional Integrator can help turn operational-debt items into normal execution commitments with:
- one owner;
- a defined outcome;
- a priority;
- a target date;
- unresolved decisions;
- recurring review.
This prevents process improvement from becoming permanent “when we have time” work.
The role helps distinguish deletion from redesign
Operational debt should not create a reflex to remove controls.
Some processes are slow because the underlying risk genuinely requires careful review.
Others are slow because the organization has layered several controls around the same risk.
The Fractional Integrator can help functional owners decide whether a process should be:
- removed completely;
- shortened;
- reassigned;
- standardized;
- automated;
- monitored differently;
- intentionally retained.
The business owner should still make the policy decision.
The Integrator helps make sure the decision is actually made and implemented across functions.
The Fractional Integrator should not become the new workaround
There is a failure mode worth avoiding.
The company hires operational support, and soon every unusual process question goes to the Fractional Integrator.
That replaces one dependency with another.
A stronger outcome is:
- Finance owns financial controls;
- Sales owns appropriate commercial rules;
- Operations owns operational workflows;
- Technology owns system implementation;
- functional leaders own their decisions and exceptions;
- the Fractional Integrator coordinates the cross-functional execution system.
The role should increase internal ownership rather than centralize every decision externally.
The work includes challenging founder-dependent controls
Operational debt often survives because the founder is the safest exception path.
Nobody knows whether an unusual discount should be approved.
Ask the founder.
Two departments disagree about a handoff.
Ask the founder.
A manager wants to remove an old report but does not know who still needs it.
Ask the founder.
These escalations can appear efficient because the founder resolves them quickly.
But every repeated founder decision can indicate a rule, authority boundary, or process owner that has not been established clearly enough.
A Fractional Integrator can help turn recurring founder decisions into:
- explicit authority;
- documented rules;
- defined exceptions;
- owned escalation paths.
That reduces debt without removing the founder from genuinely strategic decisions.
Technical teams should receive a cleaned-up process
Operational debt frequently ends up in a technology backlog.
“Automate this approval.”
“Build this report.”
“Connect these systems.”
“Replace this spreadsheet.”
Before technical implementation, leadership should determine whether the underlying workflow deserves to survive.
The Fractional Integrator can help clarify:
- the real business requirement;
- steps that should disappear;
- rules that should remain;
- authoritative data sources;
- ownership;
- exceptions;
- expected outcome.
Technology teams can then design around an intentional future process rather than digitizing historical debt.
A Fractional Integrator is not required for every company
An internal COO, Operations Leader, functional manager, or process owner may be fully capable of leading the same work.
Fractional support is more relevant when:
- debt spans several departments;
- no internal leader owns the end-to-end process;
- improvement projects repeatedly stall;
- the founder remains the default cross-functional coordinator;
- operational work needs senior ownership without a full-time executive hire;
- functional leaders need a consistent execution rhythm around process change.
It may add little value when a capable internal operator already has the authority and capacity to do this work.
The best measure is whether debt stops returning unnoticed
Removing a few inefficient processes is useful.
Creating a company that notices new debt early is more valuable.
The stronger operating system includes:
- clear process ownership;
- review dates for temporary workarounds;
- visible exceptions;
- recurring process improvement;
- clear decision rights;
- a way to retire outdated work.
A Fractional Integrator can help establish that rhythm, but the long-term objective is organizational discipline.
The goal is not to create a company with no operational debt. It is to create one that knows where the debt is, what it costs, who owns it, and when it will be repaid.
Do Not Automate a Process You Should Remove
Automation is useful when a process is necessary, repeatable, understood, and worth performing more efficiently. It becomes expensive operational debt when a company automates approvals, reports, checks, handoffs, or workarounds that should first have been removed or redesigned. Faster execution does not make an unnecessary process more valuable.
This is one of the most common mistakes in operational improvement.
A team identifies a slow process.
The immediate response is:
“Can we automate this?”
Sometimes the better question is:
“Why are we still doing this at all?”
Automation can make old assumptions harder to see
Manual processes are frustrating, but their logic is often visible.
Employees know which approval is unnecessary.
They know which spreadsheet field is entered only because another department expects it.
They know which report nobody reads.
They know which exception is handled differently from the documented process.
Once the workflow is automated, those assumptions can disappear inside:
- workflow rules;
- system configurations;
- approval matrices;
- scheduled jobs;
- integrations;
- custom code.
The process becomes faster, but also more difficult to question because the old decision is now embedded in technology.
Digitizing unnecessary approvals does not remove approval debt
Imagine a purchase request needs approval from three managers.
Leadership recognizes that waiting for email responses is slow, so the organization implements an automated approval workflow.
The new system sends notifications immediately.
It records timestamps.
It reminds approvers automatically.
The technology works exactly as designed.
But if all three managers are checking the same risk, the company has automated redundant governance.
A better redesign might ask whether:
- one approval is sufficient for normal purchases;
- higher-value requests need additional review;
- certain low-risk categories can be pre-approved;
- exceptions require escalation instead of every transaction;
- periodic auditing can replace one of the approval layers.
The automation question should come after these decisions.
Do not automate reports that no longer drive decisions
Reporting is another common source of premature automation.
A team spends hours preparing a weekly management report.
Someone proposes connecting the source systems and generating it automatically.
That may be technically sensible.
Before investing in it, ask:
- Who uses this report?
- Which decision changes because of it?
- Which fields are actually reviewed?
- Are the same metrics already available elsewhere?
- Would anyone notice if the report stopped for four weeks?
If the report no longer supports an active management decision, automation would preserve the debt instead of repaying it.
Remove duplicate data before integrating duplicate data
Integration can reduce manual entry.
It can also hide unnecessary duplication.
Suppose customer information currently moves from:
- CRM;
- operations spreadsheet;
- finance workbook;
- management dashboard.
A technical team could build integrations that keep all four synchronized.
A process review may reveal that two of those records do not need to exist.
The better design may be:
- one authoritative customer record;
- systems reading the fields they need;
- downstream views rather than duplicate master records;
- ownership of data quality at the source.
Integration is strongest when it connects necessary systems, not when it preserves every historical copy of the same information.
Standardize before automating inconsistent work
Automation requires rules.
If three teams perform the same process differently, technology cannot determine the correct version by itself.
Consider a customer onboarding process.
Team A requires five fields.
Team B requires eight.
Team C collects the information by email and enters it later.
Automating all three versions creates a more sophisticated form of inconsistency.
Before implementation, leadership should decide:
- what information is genuinely required;
- which fields are optional;
- who owns each piece of data;
- what “onboarding complete” means;
- which exceptions deserve a different path.
Once the process is consistent, automation has something stable to support.
Fix ownership before automating routing
Workflow software can send work to a person.
It cannot decide who should own a business decision when leadership has never defined that responsibility.
A request may currently bounce between Finance, Operations, and Sales.
Automating those transfers may make the bouncing faster.
The real issue may be that nobody owns the outcome.
Clarify:
- who is accountable;
- which departments provide input;
- who makes the final decision;
- which conditions trigger escalation.
Technology should route work through an ownership model leadership understands.
Separate exceptions from normal flow
Companies sometimes design automation around every exception that has ever occurred.
The result is a workflow full of branches, special cases, and approval paths that few people understand.
A stronger design begins by identifying the normal case.
Ask:
- What happens in most transactions?
- Which decisions can follow a standard rule?
- What genuinely requires human judgment?
- Which exceptions occur often enough to become a formal rule?
- Which rare cases should simply be escalated?
Normal work should remain simple.
Exceptional work can have a controlled path without making every routine transaction carry the complexity of the exception.
Automation should remove coordination work, not merely relocate it
Some automation projects move manual effort rather than eliminate it.
Employees stop entering information in one place but start reviewing an exception queue every morning.
Managers stop sending approval emails but receive constant workflow notifications.
A spreadsheet disappears, but employees now export system data into another file to perform the analysis they still need.
After implementation, review the whole workflow.
Ask whether the company actually reduced:
- human touches;
- waiting time;
- duplicate entry;
- manual checking;
- exception handling;
- management intervention.
A successful automation should reduce operational burden, not merely give the burden a new interface.
Know when automation is the right repayment action
Automation becomes a strong option when the process:
- serves a current business purpose;
- happens often enough to justify the investment;
- follows stable rules;
- uses known data sources;
- has clear ownership;
- contains predictable exception paths;
- consumes meaningful recurring manual effort.
In those conditions, automation can be a legitimate form of operational-debt repayment.
KSoft Technologies' current process automation offering describes this type of work in terms of workflow automation, system integration, and reducing repetitive manual activity. The operational design still needs to come first so that technology supports the process the business actually wants to keep.
Use the delete-before-digitize test
Before approving an automation project, leadership can use five questions:
- Purpose: Would we intentionally create this process today?
- Necessity: Which steps must remain to achieve the outcome or control the risk?
- Ownership: Is one person accountable for the process?
- Standardization: Do teams agree on the normal workflow?
- Economics: Is recurring manual effort high enough to justify automation?
If the first two questions produce weak answers, do not begin with software.
The cleanest automated workflow is sometimes the one the business decides it no longer needs.
What Does Operational Debt Look Like in a Growing Company?
Operational debt in a growing company rarely appears as one obviously broken workflow. It accumulates as teams add approvals, trackers, reports, exceptions, and manual coordination to keep up with growth. Eventually, experienced employees spend significant effort maintaining the workarounds while leadership sees only the final output.
Consider a hypothetical 75-person B2B services company.
This is an illustrative scenario, not a KSoft Technologies client case.
The company has grown from a small founder-led team into separate Sales, Operations, Finance, and Customer Success functions.
Revenue is growing.
Customers are being served.
There is no single operational crisis.
Yet managers increasingly feel that simple work requires too much coordination.
The first workaround solves a real problem
When the company had fewer than 20 employees, Sales could hand a new customer directly to the founder and delivery lead.
As volume increased, details were occasionally missed.
Operations created an onboarding spreadsheet to make sure every new project included:
- customer contacts;
- commercial terms;
- expected start date;
- delivery scope;
- assigned team;
- billing information.
The spreadsheet improves reliability.
At this stage, it is a sensible solution.
Growth adds a second layer of control
A few customers begin projects before Finance has confirmed their billing setup.
Leadership introduces a Finance approval before onboarding can be marked complete.
Finance checks:
- billing entity;
- payment terms;
- tax information;
- contract value.
The control makes sense.
But the CRM already contains some of the same information.
Nobody redesigns the data flow.
Finance starts copying values from the spreadsheet into the accounting system.
Duplicate entry has entered the process.
Customer Success creates another tracker
Customer Success wants better visibility into launches.
The team creates its own tracker showing:
- onboarding status;
- kickoff date;
- customer contacts;
- open issues;
- responsible manager.
The tracker is useful.
It also duplicates several fields from the Operations workbook.
Customer Success now asks Operations for status updates so its file remains current.
A visibility problem has created recurring coordination work.
A quality issue creates another approval
One project begins with an unrealistic delivery commitment.
To prevent the problem from repeating, leadership requires an Operations Manager to approve every new project before kickoff.
The approval is intended to verify capacity and timing.
Several months later, a resource-planning system gives Operations much better capacity visibility.
The manual approval remains.
What started as a response to a real risk has become a permanent queue.
Leadership asks for reporting because the process is hard to see
As onboarding becomes more complicated, leadership wants a weekly summary.
An Operations Analyst prepares a report from:
- CRM data;
- the onboarding spreadsheet;
- Customer Success's tracker;
- Finance status;
- resource-planning information.
Preparing the report requires manual reconciliation because the systems do not always agree.
Leadership receives one clean summary.
The operating debt required to create that summary remains largely invisible.
Experienced employees begin protecting the process
Two employees now understand how the workflow really works.
They know:
- which CRM field is unreliable;
- which Finance approval can be accelerated;
- which customers require special handling;
- when Operations can proceed before every field is complete;
- which status in the Customer Success tracker actually means the project is ready.
Their experience makes the workflow functional.
It also hides how much unwritten logic the process now contains.
The founder becomes the exception path
A strategic customer needs an urgent start.
Finance has not completed the normal approval.
Operations is unsure whether it can assign capacity.
Sales argues that waiting will damage the relationship.
Nobody owns the cross-functional exception.
The founder approves it.
The next unusual customer follows the same pattern.
Founder intervention has become another unofficial step in the process.
Leadership initially asks for a new onboarding system
The obvious solution appears to be software.
The company considers replacing the spreadsheets and trackers with one custom workflow.
Before implementation, the process is mapped from beginning to end.
The review reveals that the company is not dealing with one software problem.
It is carrying several forms of operational debt:
- duplicate customer data;
- an approval added for a risk now controlled elsewhere;
- inconsistent status definitions;
- a management report created because workflow visibility is poor;
- undocumented exception rules;
- founder-dependent escalation;
- overlapping team trackers.
The company removes debt before designing the new workflow
Leadership starts by defining the desired operating process.
Customer information should originate from one authoritative record.
Finance should receive only the information required for financial setup.
Operations should review only projects that cross defined capacity or delivery-risk thresholds.
Customer Success should see onboarding status without maintaining a duplicate master tracker.
Standard cases should move without founder involvement.
Exceptions should have one named decision owner.
The weekly report should contain only metrics leadership actually uses.
Some steps disappear entirely
The process review leads to several deliberate removals.
One spreadsheet is retired.
Several duplicate fields disappear.
Routine Operations approval is replaced with defined exception conditions.
Customer Success no longer maintains a separate onboarding status record.
Leadership stops receiving fields in the weekly report that nobody uses.
The future system therefore has less to automate than the original process had to perform.
Ownership becomes part of the redesign
Sales owns accurate commercial handoff information.
Finance owns financial readiness.
Operations owns delivery readiness and capacity exceptions.
Customer Success consumes shared status rather than recreating it.
One cross-functional owner is accountable for onboarding performance.
Founder approval is reserved for explicitly defined strategic exceptions.
The process is now easier to implement technically because the organization has made the operating decisions first.
Technology supports the clean process
Only after simplification does the company decide where automation is useful.
The future workflow may:
- pull customer information from the CRM;
- route financial setup to Finance;
- trigger Operations review only when defined conditions apply;
- expose one shared onboarding status;
- notify owners when a task is blocked;
- route genuine exceptions to the correct decision-maker;
- provide leadership reporting from the same process data.
Technology is now reducing coordination instead of reproducing it.
The real improvement is a smaller operating burden
The company may describe the final initiative as an automation project.
But the most important work happened before the automation.
Leadership questioned old controls.
Removed duplicate work.
Standardized status definitions.
Assigned ownership.
Defined exceptions.
Reduced founder dependency.
Only then did technology make the cleaner process easier to execute.
Paying down operational debt is not about making every old process run faster. It is about deciding which parts of the old process deserve to survive at all.
Can Your Existing Team Pay Down Operational Debt?
Yes. An existing leadership team can repay operational debt when someone has clear authority, enough capacity, cross-functional visibility, and responsibility for following improvements through to completion. Outside support becomes more relevant when debt spans several departments, improvement work repeatedly stalls, or the founder remains the person who connects unresolved operational issues.
Operational debt does not automatically require a consultant, Fractional Integrator, or new executive.
Many companies already have capable leaders who understand the processes better than any outside person could.
The real question is whether those leaders can convert that knowledge into completed cross-functional change.
Start with the natural process owner
Every debt item should ultimately belong to a role with enough authority to change the process.
The right owner depends on the outcome involved.
For example:
- Finance may own payment controls or financial reporting;
- Sales leadership may own commercial approvals;
- Operations may own delivery workflows and handoffs;
- HR may own employee onboarding processes;
- Technology may own system architecture and integrations.
The person who performs the most manual work is not necessarily the process owner.
An analyst may prepare a report every week, but leadership may own the decision about whether that report should exist.
An administrator may maintain an approval tracker, but the business leader responsible for the underlying control should decide whether the approval is still necessary.
Internal ownership needs real authority
Paying down operational debt often requires challenging established behavior.
The owner may need to ask:
- Why do we still require this approval?
- Why are two departments maintaining the same information?
- Why does this report exist?
- Why does this exception still require executive involvement?
- Why are employees using a workaround outside the formal system?
- Why do we have three definitions of the same status?
Those questions can be uncomfortable because they challenge work people have performed faithfully for years.
A process owner needs enough authority to distinguish:
- “this has always been done” from “this still needs to be done”;
- historical preference from current policy;
- useful controls from inherited duplication.
Without that authority, an internal improvement effort may document the debt without actually removing it.
Capacity is often the limiting factor
A capable leader may already know what needs to change.
The difficulty is finding enough protected time to make the change happen.
Operational debt repayment competes with:
- customer escalations;
- delivery deadlines;
- hiring;
- monthly reporting;
- sales support;
- team management;
- urgent leadership requests.
Process improvement is easy to postpone because the old process still works.
Employees continue compensating for the debt, so today's urgent work wins.
A month later, the same improvement remains open.
Before assigning repayment internally, leadership should ask:
- What will this leader stop doing to create room for the work?
- Can they coordinate every department involved?
- Can they stay accountable until the old process is actually retired?
- Will daily operational issues repeatedly displace the work?
Ownership without capacity often produces another backlog rather than repayment.
Cross-functional debt needs cross-functional visibility
Some operational debt belongs clearly to one department.
Much of the expensive debt does not.
Consider a customer onboarding delay.
Sales may believe Finance approval is the problem.
Finance may believe Sales provides incomplete information.
Operations may be waiting for a delivery date.
Customer Success may maintain a separate tracker because none of the other systems show end-to-end status.
Each team can improve its own step and the overall workflow may still remain slow.
The owner needs visibility across:
- the trigger;
- every handoff;
- required information;
- approvals;
- exceptions;
- final outcome.
Without that end-to-end view, departments may optimize their own work while leaving the underlying debt untouched.
Internal teams need permission to stop work, not only improve it
Many process-improvement initiatives are framed around:
“How can we do this faster?”
That assumes the work deserves to continue.
A stronger internal mandate includes the ability to recommend:
- stopping a report;
- removing an approval;
- retiring a spreadsheet;
- eliminating duplicate entry;
- removing a redundant check;
- changing an old policy.
A team that is allowed only to streamline work will preserve debt that should have been deleted.
Process owners need cooperation from technology
Some debt can be repaid through policy and process changes alone.
Other debt remains because systems do not support the desired workflow.
Internal Technology or Development teams may need to help with:
- system integrations;
- workflow automation;
- data synchronization;
- access controls;
- notifications;
- reporting;
- custom application changes.
The business owner should still define the process.
Technology should not be asked to decide whether an approval is necessary, which exception is valid, or which department should own a business outcome.
Those are operating decisions.
Create a small internal repayment cadence
Operational debt does not always need a large transformation program.
A leadership team can begin with a small recurring rhythm.
For example:
- identify the highest-cost debt items;
- select a small number for active repayment;
- assign one owner to each;
- define the desired operating outcome;
- resolve cross-functional decisions;
- review progress regularly;
- verify that the old process has been retired.
This matters because operational debt competes with urgent work.
If repayment has no place in the operating rhythm, it will usually be displaced by today's problem.
Watch for improvement projects that never close
One of the clearest signals that internal ownership is insufficient is a backlog full of familiar process issues.
Everyone agrees they should be fixed.
Nobody disagrees with the solution.
Yet they remain open for months.
Examples include:
- “We need to clean up the approval flow.”
- “We should connect the CRM and finance system.”
- “We need one source of truth.”
- “We should stop maintaining this spreadsheet.”
- “Someone needs to redesign customer onboarding.”
Repeated agreement without completion is itself an execution problem.
The company may not need more ideas.
It may need stronger ownership of the improvement system.
Four conditions make internal repayment more likely to work
Leadership can evaluate internal readiness using four conditions:
- Authority: Can the owner change rules, approvals, roles, and workflows?
- Capacity: Does the owner have enough protected time to drive repayment through completion?
- Visibility: Can the owner see the full process across functions?
- Continuity: Will the owner remain accountable from diagnosis through implementation and retirement of the old process?
When these four conditions exist, an internal leader may be the strongest option.
When outside operational support becomes useful
A Fractional Integrator may be useful when the problem is not a lack of capable people but a lack of cross-functional ownership.
Common signals include:
- several departments are involved but none owns the end-to-end process;
- managers agree on improvements but implementation repeatedly stalls;
- the founder is still resolving routine cross-functional exceptions;
- Technology is waiting for leadership to define the future process;
- teams disagree about which system or data source is authoritative;
- operational improvement continually loses priority to daily execution;
- no one owns the operational-debt backlog as a business system.
In those situations, outside support can provide coordination and execution discipline without replacing functional ownership.
A Fractional Integrator should strengthen internal owners
The role should not become a permanent clearinghouse for every process problem.
A healthier model is for the Fractional Integrator to help:
- identify and prioritize debt;
- clarify accountable owners;
- organize cross-functional decisions;
- challenge outdated process assumptions;
- keep repayment work moving;
- coordinate business and technical implementation;
- verify that old processes are retired.
Functional leaders should still own the policies and outcomes within their responsibilities.
The outside operator connects those responsibilities into one execution system.
Outside support may add little value when an internal operator already owns the work
Fractional support is not automatically necessary because processes are inefficient.
The existing team may be fully equipped when:
- a COO or Operations Leader already owns cross-functional execution;
- functional decision rights are clear;
- leaders have enough time to work on process improvement;
- improvement projects consistently reach completion;
- business and technology teams collaborate effectively;
- the founder has delegated appropriate operating authority.
In that case, the company should use the operating capability it already has.
Outside support cannot compensate for leadership that refuses to make decisions
Operational debt repayment still requires leadership choices.
A Fractional Integrator cannot effectively remove debt when:
- nobody will own the process;
- leaders refuse to remove outdated controls;
- the founder retains every decision;
- departments will not cooperate;
- leadership priorities change constantly;
- the organization wants automation without defining the desired process.
An outside operator can create structure around decisions.
The business still has to make them.
Match the solution to the capability gap
“We have too much operational debt” can describe several different problems.
The company may need:
- Process ownership because nobody controls the end-to-end workflow;
- Process redesign because historical steps no longer serve the business;
- Integration because employees manually connect systems;
- Automation because a stable repetitive process consumes unnecessary effort;
- Documentation because critical knowledge sits with individuals;
- Fractional operational leadership because several functions must coordinate repayment and nobody has the capacity to own it.
Those are different problems.
They should not automatically receive the same solution.
Use one ownership question to decide the next step
Leadership does not need to begin by asking:
“Do we need a Fractional Integrator?”
A better question is:
“Who has the authority, capacity, and cross-functional responsibility to identify this operational debt, make the required decisions, and keep the repayment work moving until the old process is gone?”
If the company already has a clear answer, empower that person and protect the time required.
If the answer keeps returning to the founder—or to nobody—the ownership gap is part of the operational debt.
Build Operations That Do Not Recreate the Debt
Paying down operational debt is only half the work. The stronger operating system makes new debt visible before temporary workarounds, extra approvals, duplicate records, and manual checks become permanent. That requires clear ownership, review dates, controlled exceptions, deliberate process retirement, and regular attention to recurring friction.
Operational debt will never disappear completely.
Nor should the goal be zero debt.
Growing companies need temporary solutions.
Teams need room to experiment.
Leaders sometimes need to add controls quickly before a better solution exists.
The problem begins when temporary work loses its temporary status.
Give every workaround an owner
A temporary process without an owner has a strong chance of becoming permanent.
Whenever the company introduces a workaround, assign someone who is responsible for answering:
- Why does this workaround exist?
- Which problem does it solve?
- What recurring effort does it create?
- What condition would allow us to remove it?
- When will we review it?
Ownership does not mean that person must personally perform every step.
It means someone remains accountable for deciding whether the workaround still belongs in the operating model.
Put expiration dates on temporary controls
Many forms of operational debt begin with sensible controls.
A customer problem creates an additional review.
A financial mistake creates an approval.
A system issue creates a manual check.
A reporting gap creates a spreadsheet.
Instead of assuming the new control lasts forever, define a review date when it is introduced.
The review can ask:
- Does the original risk still exist?
- Has another control replaced this step?
- How often has the control caught a meaningful problem?
- Has the process changed enough to require redesign?
- Can the same risk now be managed with less recurring effort?
A review date converts “temporary” from a verbal intention into an operating commitment.
Track exceptions because they reveal future debt
Exceptions are one of the best sources of process intelligence.
If employees repeatedly need to bypass, override, or reinterpret a rule, something deserves attention.
The business should be able to see:
- which exceptions occur;
- how often they occur;
- who approves them;
- why they are needed;
- whether the same exception keeps returning.
Repeated exceptions may indicate that the documented process no longer matches reality.
At that point, leadership should decide whether the exception should become a standard rule, remain controlled, or trigger a broader process redesign.
Make process ownership visible
A workflow should not become ownerless simply because several departments participate in it.
Cross-functional processes still need one accountable owner for overall health.
That owner should be able to answer:
- What outcome is this process expected to create?
- Which teams participate?
- Where are the current bottlenecks?
- Which measures indicate that the process is working?
- Which debt items are currently open?
- Which changes are being implemented?
Without visible ownership, process maintenance tends to become everyone's secondary responsibility and nobody's primary accountability.
Review the process when the business changes
A process can be well designed today and create debt later.
Company conditions change.
Volume increases.
New products appear.
Customer segments change.
Systems are replaced.
Teams reorganize.
Risk tolerance changes.
Leadership should revisit important workflows when those conditions materially change.
A process designed for 15 employees may not be appropriate for 100.
A control created before system validation existed may no longer be necessary after implementation.
A report designed for one management structure may no longer serve the current leadership team.
Process design should evolve with the operating environment.
Stop measuring activity that no longer informs a decision
Metrics can accumulate operational debt too.
A dashboard begins with ten useful measures.
Over time, leaders request additional fields.
Nobody removes the old ones.
Employees spend increasing time collecting information while leadership pays attention to only a fraction of it.
Every recurring metric should have a reason to exist.
Ask:
- What decision does this metric inform?
- Who owns that decision?
- What action occurs when the number changes?
- How frequently is the measure actually needed?
If nobody can connect the metric to an operating decision, the measurement process itself may be debt.
Design new processes around the normal case
Processes become difficult to operate when every unusual historical event becomes part of the standard workflow.
Start with the normal case.
Define:
- what normally triggers the process;
- what information is normally required;
- who normally owns each stage;
- what normal approval is required;
- what successful completion means.
Then create specific paths for genuine exceptions.
This prevents every standard transaction from carrying the complexity of rare edge cases.
Prevent parallel systems after process changes
New operational debt often appears immediately after an improvement project.
The organization introduces a new system but keeps the old tracker.
A new dashboard launches but managers continue asking for the spreadsheet.
Automated notifications begin, but employees keep sending manual reminders.
A redesigned approval flow goes live while the previous email-based approval remains accepted.
These parallel systems are understandable during a short transition.
They become debt when the transition never ends.
Every process rollout should define:
- what becomes the new source of truth;
- when the old method stops;
- who confirms adoption;
- what happens to historical data;
- how legitimate gaps in the new process will be handled.
A new process is not fully implemented while the business still relies on the old one to feel safe.
Treat recurring manual work as a signal, not automatically a failure
Manual work is not inherently operational debt.
Some activities occur too rarely to automate economically.
Some require judgment.
Some change too often to standardize.
Some carry enough risk that human review is appropriate.
The question is whether the manual work is intentional.
Healthy manual processes have:
- a known purpose;
- clear ownership;
- an appropriate level of effort;
- understood risks;
- a reason automation is unnecessary or premature.
Debt is different.
Debt is recurring effort the company continues to carry without a current deliberate decision.
Create a regular operational-debt review
Operational debt should have a place in the leadership rhythm.
The review does not need to become another long meeting.
Leadership can periodically ask:
- Which manual work has increased significantly?
- Which approval queues are slowing execution?
- Which reports appear unused?
- Which spreadsheets have become operationally critical?
- Which exceptions keep repeating?
- Which managers are spending time coordinating routine work?
- Which temporary workarounds are still active?
- Which processes now depend too heavily on one person?
The purpose is not to create a permanent optimization program.
It is to prevent recurring friction from disappearing into normal work.
Keep a small repayment backlog instead of a giant transformation list
An organization can identify dozens of improvement opportunities quickly.
Trying to fix all of them at once usually reduces focus.
Maintain a visible backlog and actively work on only the debt with the strongest combination of:
- recurring cost;
- business impact;
- execution friction;
- reasonable repayment effort.
Completing a few meaningful repayments is more valuable than documenting fifty problems that remain open.
Make retirement part of the definition of done
Process improvement is not complete when the new workflow launches.
It is complete when the old burden stops.
For every repayment initiative, the definition of done should answer:
- Which old activity no longer occurs?
- Which approval disappeared?
- Which spreadsheet was retired?
- Which duplicate entry ended?
- Which report stopped?
- Which escalation moved to a clear owner?
If the old work continues after the improvement project closes, the debt was not fully repaid.
Test whether your operations are becoming easier or merely larger
Growth naturally increases work.
It should not require every operating process to become proportionally more complicated.
Leadership can test the operating system with questions such as:
- Are approvals increasing faster than actual risk?
- Are managers spending more time coordinating routine work?
- Are teams creating more spreadsheets to compensate for system gaps?
- Are new employees learning more exceptions than clear rules?
- Are reports multiplying without clearer decisions?
- Are senior leaders increasingly required to resolve ordinary workflow issues?
A growing organization will become more sophisticated.
Sophistication does not need to mean accumulated friction.
The operating system should periodically challenge its own history
Technical teams expect codebases to change.
Operations should expect the same from business processes.
A workflow that made sense two years ago may no longer deserve its current form.
A report that once helped leadership may now be redundant.
An approval created during a risky period may no longer be necessary.
A spreadsheet built as a temporary bridge may have become an invisible business system.
Mature operations preserve what still works and challenge what the business is carrying only because of history.
Operational debt should become a leadership concern before it becomes a crisis
The warning signs are often ordinary:
more approvals;
more trackers;
more manual checks;
more reporting;
more status chasing;
more “temporary” exceptions.
None of those automatically means the company is poorly run.
They mean the operating system is changing and deserves review.
The goal is not to eliminate every workaround. It is to stop yesterday's workaround from becoming tomorrow's permanent operating cost without anyone deciding that it should.
Choose one recurring process this week that your team describes as “just how we do it.”
Ask why every step exists.
Identify what risk or outcome each one protects.
Measure the recurring effort.
Then decide deliberately whether each step should remain, change, or disappear.
That is how operational debt starts becoming visible—and repayable.
Stop Letting Yesterday’s Workarounds Become Permanent Costs
Identify the approvals, handoffs, reports, manual checks, and duplicate work your business has outgrown, then build a practical repayment plan with clear ownership.
Discuss Your Operational DebtFrequently Asked Questions
What is operational debt?
Operational debt is the recurring burden created when temporary workarounds, outdated approvals, duplicate data entry, unnecessary reports, manual checks, or poorly designed workflows remain in place after their original purpose has changed. The process may still function, but the organization keeps paying through extra effort, delays, rework, and management attention.
Why does operational debt build up in growing companies?
Operational debt builds because companies solve immediate problems faster than they revisit old solutions. New approvals, spreadsheets, checks, and reporting routines are often reasonable when introduced. As the business changes, those temporary controls remain, new work is added around them, and employees gradually treat historical workarounds as permanent operating requirements.
How can leaders identify operational debt in everyday processes?
Look for repeated manual work, duplicate entry, multiple approvals for the same risk, recurring status chasing, reports with unclear users, frequent exceptions, parallel spreadsheets, and workflows that depend heavily on one experienced employee. A useful test is to ask why each recurring step exists and whether leadership would intentionally design it that way today.
How should a company measure the cost of operational debt?
Measure more than employee time. Consider frequency, number of people involved, waiting time, rework, management intervention, system switching, training complexity, and customer or delivery delays. The goal is not perfect financial precision. Leadership needs enough evidence to compare debt items and decide which recurring burdens deserve repayment first.
Should every manual process be considered operational debt?
No. Manual work can be appropriate when an activity is infrequent, judgment-heavy, still changing, or too small to justify automation. It becomes operational debt when recurring effort continues without a current deliberate reason, clear owner, appropriate control value, or periodic review of whether the work should still exist.
Should operational debt always be solved with automation?
No. A process should be reviewed before it is automated. Leadership may discover that a step should be removed, simplified, standardized, or reassigned instead. Automation is strongest when the process serves a current purpose, follows stable rules, has clear ownership, uses reliable data, and creates enough recurring manual effort to justify implementation.
What does a Fractional Integrator do about operational debt?
A Fractional Integrator can help leadership identify cross-functional debt, clarify ownership, prioritize repayment work, challenge outdated process assumptions, coordinate decisions, and keep improvements moving to completion. The role is especially relevant when several departments contribute to the problem but no internal leader consistently owns the full end-to-end operating outcome.
Is a Fractional Integrator the same as an Operations Manager?
No. An Operations Manager typically manages defined workflows, teams, or department-level operations. A Fractional Integrator generally focuses more broadly on cross-functional execution, accountability, ownership, and coordination across leadership priorities. Either role may help reduce operational debt; the right choice depends on whether the problem is departmental or spans the wider organization.
Can an internal leadership team reduce operational debt without outside support?
Yes. Internal improvement can work well when a capable leader has authority to change processes, enough capacity to drive the work, visibility across departments, and responsibility through implementation. Outside support becomes more useful when cross-functional improvements repeatedly stall, ownership remains unclear, or the founder continues acting as the default coordinator.
When should a company start paying down operational debt?
Start when recurring friction becomes visible enough to prioritize, rather than waiting for a major failure. Strong candidates include high-frequency manual work, growing approval queues, repeated exceptions, duplicate reporting, founder escalations, and processes that become harder to change as the company grows. Repayment can begin with one high-impact workflow rather than a company-wide transformation.
How much does operational debt reduction typically cost?
Cost depends on the type of debt and the repayment approach. Removing an unnecessary report may require almost no technology, while integration, workflow automation, ERP changes, or custom development may require significant implementation work. The company should first define the process problem, ownership gap, recurring cost, systems involved, and desired future workflow before estimating investment.
What is the first step to reducing operational debt?
Choose one recurring process that creates visible friction and map every step from trigger to completion. For each step, document its purpose, owner, frequency, effort, risk, dependencies, and exceptions. Then decide whether it should be removed, simplified, standardized, automated, or intentionally retained. One completed repayment is more useful than a long unresolved improvement list.